Stock of the Day

August 29, 2022

Illumina (ILMN)

$262.54
-$5.39 (-2.0%)
Market Cap: $39.64B

About Illumina

Illumina, Inc. offers sequencing- and array-based solutions for genetic and genomic analysis in the United States, Singapore, the United Kingdom, and internationally. It operates through Core Illumina and GRAIL segments. The company offers sequencing and array-based instruments and consumables, which include reagents, flow cells, and library preparation; whole-genome sequencing kits, which sequence entire genomes of various size and complexity; and targeted resequencing kits, which sequence exomes, specific genes, and RNA or other genomic regions of interest. It also provides whole-genome sequencing, genotyping, noninvasive prenatal testing, and product support services; and Galleri, a multi-cancer early detection test. In addition, the company is developing solutions to help accelerate cancer diagnoses, blood-based detection for minimal residual disease, and other post-diagnostic applications. The company serves genomic research centers, academic institutions, government laboratories, and hospitals, as well as pharmaceutical, biotechnology, commercial molecular diagnostic laboratories, and consumer genomics companies. It markets and distributes its products directly to customers, as well as through life-science distributors. Illumina, Inc. was incorporated in 1998 and is based in San Diego, California.

Illumina Bull Case

Here are some ways that investors could benefit from investing in Illumina, Inc.:

  • Illumina, Inc. recently released SpliceAI2, a new genomic AI model that helps researchers identify disease-relevant splice variants, which is a significant advancement for rare disease research and drug discovery that positions the company at the forefront of AI-driven genomics.
  • The company's stock is currently trading at $264.57, reflecting a strong upward trend from its 52-week low of $88.00, driven by its recent addition to the S&P 500 index which typically attracts significant demand from index-tracking funds.
  • Analysts from RBC Capital Markets have characterized Illumina's clinical sequencing revenue as a durable mid-teens growth opportunity, suggesting that the company has a stable and expanding revenue stream from a high-demand sector.
  • Illumina, Inc. has consistently beaten earnings expectations, reporting $1.31 in earnings per share for the most recent quarter against a consensus estimate of $1.23, demonstrating strong operational performance and profitability with a net margin of 18.36%.
  • The company has raised its full-year 2026 adjusted EPS guidance to $5.30–$5.40, indicating management confidence in continued growth and providing a solid fundamental foundation for the stock's valuation.

Illumina Bear Case

Investors should be bearish about investing in Illumina, Inc. for these reasons:

  • Despite the recent rally, the consensus rating from eighteen brokerages remains "Hold" with an average 12-month price objective of $219.69, which is significantly below the current stock price of $264.57, suggesting that the stock may be overvalued relative to analyst expectations.
  • Insider selling has been substantial, with Director Keith Meister selling over 119,000 shares in September 2026 alone, and insiders collectively selling over 2 million shares worth approximately $436 million in the last three months, which may signal a lack of confidence from those closest to the company.
  • Barclays has maintained an "underweight" rating on Illumina, Inc. with a price target of $200, arguing that current expectations and valuation have outpaced near-term fundamentals, indicating that the stock's recent gains may not be sustainable.
  • The company's P/E ratio of 51.99 is relatively high, which means investors are paying a premium for each dollar of earnings, and this elevated valuation could make the stock more vulnerable to price corrections if growth slows or market sentiment shifts.
  • Short interest has been increasing, with the number of shares shorted rising to over 10.5 million in the most recent reporting period, indicating that a significant portion of the market is betting against the stock's future performance.

Agilent Technologies Proves Its Worth VS Illumina 

Written By Thomas Hughes on 8/17/2022
Agilent Technologies Proves Its Worth VS Illumina 

Agilent Technologies (NYSE: A) is a highly-valued stock for the low 0.6% dividend that it pays but the Q2 results once again prove the company’s worth. The results include a top and bottom line beat as well as improved guidance that has the shares moving higher in their wake. With competitors in the medical instruments/technology industry like Illumina (NASDAQ: ILMN) trading at even higher valuations and not paying a dividend, it looks like Agilent Technologies and its blue-chip status is the better choice for investors and the analyst agree. 

The analysts have a Hold rating on Illumina compared to the Moderate Buy Agilent Technologies is pegged to and the sentiment for Agilent is on the upswing. Illumina notched a handful of analysts' commentaries in the wake of its earnings report that all included price target reductions that have the consensus about 20% above the current price action. That is a larger margin of an upside than what is expected for Agilent, about 15%, but the trend in sentiment is far more favorable. 

Agilent’s report sparked a minimum of 4 analyst commentaries that all include a price target increase. According to Marketbeat.com analyst tracking tools, the price target increases have the consensus firming after a slight retreat from the high set earlier this year. The takeaway is that sentiment for Illumina is cooling while the opposite is happening for Agilent. As far as the valuation is concerned, Agilent is trading at about 27X its earnings while Illumina trades at a far higher 80X of its earnings. In this light, with one producing outperformance and increasing the guidance and the other underperforming and lowering guidance, the stage is set for one’s value to improve and the others to crumble and Agilent is already outperforming the other. 

Agilent Technologies Pops After Nimble Q3 Execution

Agilent Technologies had a great quarter with revenue of $1.72 billion rising 8.2% over last year to beat the consensus figures by 480 basis points. The strength was driven by gains in all segments led by a 14% increase in Life Sciences offset by smaller 5% and 2% gains in CrossLab and Diagnostics. The good news, however, is in the margin and guidance which are both favorable to cash flow and the dividend. The company reports a 28% increase in GAAP earnings and a 22% increase in adjusted earnings that outpaced revenue growth by a wide margin. The $1.34 in adjusted EPS also beat the consensus estimate by $0.13 and the strength is expected to carry through into the 4th quarter at least. 

The company raised the outlook for the 4th quarter and the year to expect FY EPS in the range of $5.06 to $5.08 but there is a caveat and an offsetting factor to consider. The caveat is that EPS and revenue guidance were raised to match the consensus figure, the offsetting factor is that consensus has been on the rise over the past few months and accelerated the movement a week prior to the release. 

Agilent Outperforms Illumina 

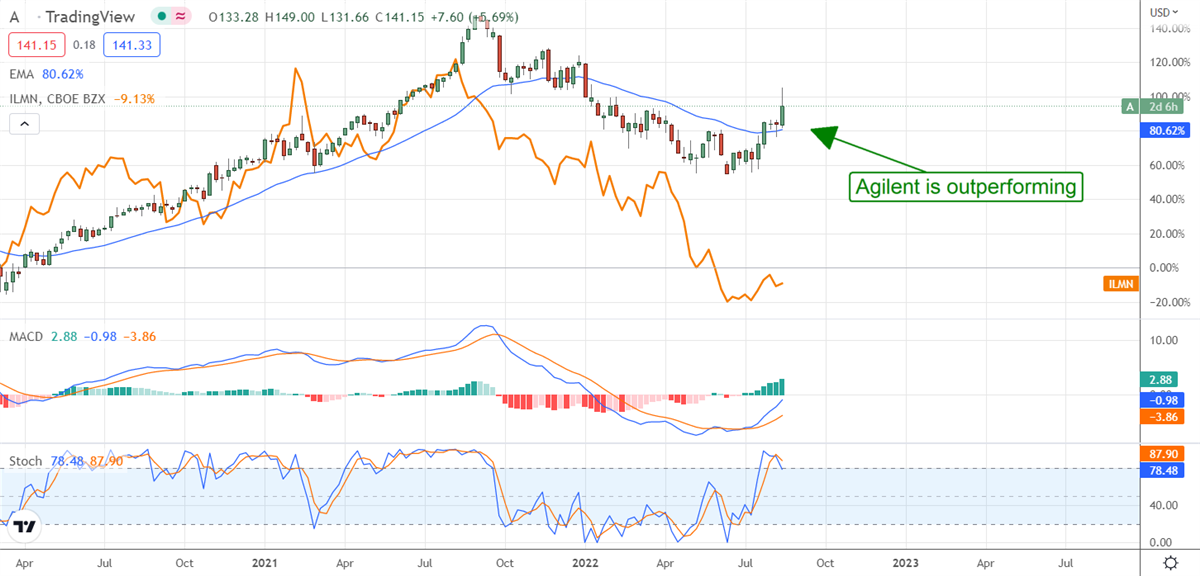
The price action in Agilent Technologies tracked in line with Illumina for the first few quarters of the pandemic but the action diverged in late 2021. Since then, Illumina and its niche markets have proven to be more volatile than Agilent and its broader-based clientele with Agilent up 100% versus the other. Based on the latest report investors would be wise to assume Agilent will continue to be less volatile as well as pay its dividend. 
Agilent Technologies Proves Its Worth VS Illumina 

Recent News