Stock of the Day

March 25, 2024

Adobe (ADBE)

$251.67
+$10.99 (+4.6%)
Market Cap: $93.67B

About Adobe

Adobe Inc., together with its subsidiaries, operates as a diversified software company worldwide. It operates through three segments: Digital Media, Digital Experience, and Publishing and Advertising. The Digital Media segment offers products, services, and solutions that enable individuals, teams, and enterprises to create, publish, and promote content; and Document Cloud, a unified cloud-based document services platform. Its flagship product is Creative Cloud, a subscription service that allows members to access its creative products. This segment serves content creators, students, workers, marketers, educators, enthusiasts, and communicators. The Digital Experience segment provides an integrated platform and set of applications and services that enable brands and businesses to create, manage, execute, measure, monetize, and optimize customer experiences from analytics to commerce. This segment serves marketers, advertisers, agencies, publishers, merchandisers, merchants, web analysts, data scientists, developers, and executives across the C-suite. The Publishing and Advertising segment offers products and services, such as e-learning solutions, technical document publishing, web conferencing, document and forms platform, web application development, and high-end printing, as well as Advertising Cloud offerings. It also provides consulting, technical support, and learning services. The company offers its products and services directly to enterprise customers through its sales force and local field offices, as well as to end users through app stores and through its website at adobe.com. It also distributes products and services through distributors, value-added resellers, systems integrators, software vendors and developers, retailers, and original equipment manufacturers. The company was formerly known as Adobe Systems Incorporated and changed its name to Adobe Inc. in October 2018. Adobe Inc. was founded in 1982 and is headquartered in San Jose, California.

Adobe Bull Case

Here are some ways that investors could benefit from investing in Adobe:

  • Adobe's stock is currently trading at $238.14, which represents a significant discount to the consensus price target of $282.68, suggesting substantial upside potential for investors who believe the recent sell-off has been an overreaction to temporary market fears.
  • The company demonstrated strong fundamental performance in its most recent quarter, reporting earnings per share of $6.13, which beat analyst estimates of $6.08, while also raising its full-year 2026 guidance to $24.45-$24.50, indicating management confidence in continued growth despite market volatility.
  • Adobe maintains a highly profitable business model with a net margin of 28.05% and a return on equity of 65.65%, metrics that reflect its ability to generate substantial cash flow from its subscription-based Digital Media and Digital Experience segments.
  • With a P/E ratio of 13.29, Adobe is trading at a valuation multiple that is historically low for a software company with double-digit revenue growth, potentially offering a more attractive entry point compared to its peers in the enterprise software sector.
  • The company continues to expand its AI capabilities, such as the recent partnership with Heathrow Airport to integrate AI agents into customer journeys, which positions Adobe to capture new revenue streams from enterprise AI adoption beyond its traditional creative tools.

Adobe Bear Case

Investors should be bearish about investing in Adobe for these reasons:

  • Wells Fargo recently downgraded Adobe to Underweight and cut its price target to $225, citing concerns that the company is losing budget share to competitors as CIOs shift spending toward other AI software offerings, which could pressure future revenue growth.
  • Analysts have raised concerns about "meaningful cracks" in Adobe's organic growth, noting that the company may need to nearly double its new recurring revenue to meet its targets, suggesting that the current growth rate may not be sustainable without significant new product adoption.
  • The stock has experienced significant volatility and a decline of approximately 30% this year, underperforming many of its enterprise software peers, which may indicate broader market skepticism about Adobe's long-term competitive position in the AI era.
  • There is growing competition from AI-native tools, including open-source and AI-generated clones of Adobe's creative suite, which could erode Adobe's pricing power and force it to lower subscription prices to retain customers.
  • Insider selling activity, including recent large sales by CEO Shantanu Narayen, may signal a lack of confidence among company executives in the stock's near-term performance, which can weigh on investor sentiment.

Adobe Stock Reaches Turning Point as Market Outlook Resets

Written By Thomas Hughes on 3/15/2024

Adobe stock price

Adobe’s (NASDAQ: ADBE) solid performance and outlook for growth will continue to support the price action over time, suggesting a buying opportunity with the post-release dip. The market is down more than 10% in pre-market action, not on signs of weakening but because guidance aligns with the market’s expectations. That led analysts to trim targets for the stock and add downward pressure to the action.

As-expected guidance suggests momentum in AI is waning, which is far from the truth. While economic conditions impact business spending, AI's outlook remains robust. The AI market is projected to grow at a 15% CAGR for the foreseeable future, with cash flow centered on the largest operators able to handle enterprise-level business. Because the FOMC is expected to cut rates later this year and reinvigorate the economy, investors should expect Adobe’s performance to gain momentum in the back half and outperform the cautious guidance. 

Did Adobe Miss Projections for Q1 Results? 

Adobe Q1 results outperformed on the top and bottom lines; it did not miss projections. The company produced a record $5.18 billion in net revenue for a gain of 11.2% that outpaced the consensus by $0.030 billion. The strength was driven by a 12% gain in Digital Media and a 10% increase in Digital Experience. Digital Media results included record net new Document ARR, while DIgital Experience experienced a 12% increase in subscriptions. RPO, a leading indicator of business, is up 16% and setting a record. 

The margin news is good. The company widened the gross margin and adjusted operating margin and expects margin strength to persist. The GAAP results are impacted by a one-time charge related to the Figma-deal exit, but adjusted results are promising. The adjusted $4.48 is up 17.9% YOY and outpaced the Marketbeat consensus by a dime. 

Exiting the Figma deal is noteworthy for several reasons, including market skepticism and financial health. The company was prepped for the closing and is now in excellent financial shape, able to sustain and increase the share repurchase program while maintaining a fortress balance sheet. Repurchases in Q1 amounted to 3.1 million shares, bringing the quarter-end comparison down by 1.3%. The new authorization is worth $25 billion or more than 10% of the newly lowered market cap. 

Guidance is good but not enough to catalyze bullish behavior. The company forecast revenue of $5.25 to $5.30 for sequential growth and a YOY gain of 9%. The bad news is that analysts forecasted slightly more on the top line, and YOY gains are decreasing. The good news is that margins are expected to widen, producing EPS that aligns with the consensus. Adobe has a history of outperformance, beating estimates on the top and bottom line 100% of the time on a TTM basis. 

What do Analysts Say About Adobe’s Guidance? 

The analysts' response is tepid, with most lowering their price targets following the release. However, sentiment remains firmly bullish, with the stock pegged at Moderate Buy and 20% upside at the consensus figure. The analysts are trimming their targets and lowering the range’s high end, but most new revisions are above consensus and continue to lead the market. Takeaways from the analyst chatter are that price increases will aid 2nd half results, the company is growing its user base and building leverage for future sales, and the repurchases are a sign of financial strength. 

Adobe’s shares fell more than 10% to trade near a critical support target. This target aligns with recent lows and a trading range in place since last year. Technical speaking, the market is at a crucial inflection point that could result in a rebound or a much deeper decline. A more profound decline could take the market to $400 or lower, which is unexpected. Assuming the market confirms support at or near the current levels, price action would be consistent with a Head & Shoulders Pattern. In this scenario, the market would confirm support at the mid-point of a larger trading range, bringing targets near $680 and the range top into play. 
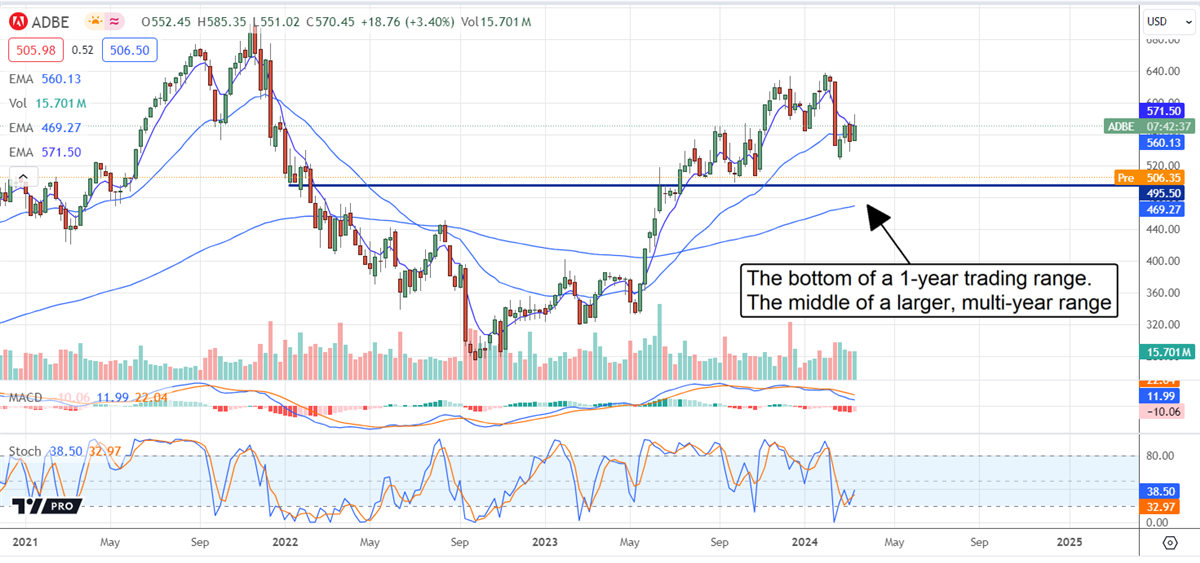
Adobe stock chart price outlook

Recent News