Stock of the Day

May 6, 2024

Starbucks (SBUX)

$96.88
+$3.63 (+3.9%)
Market Cap: $106.31B

About Starbucks

Starbucks Corporation, together with its subsidiaries, operates as a roaster, marketer, and retailer of coffee worldwide. The company operates through three segments: North America, International, and Channel Development. Its stores offer coffee and tea beverages, roasted whole beans and ground coffees, single serve products, and ready-to-drink beverages; and various food products, such as pastries, breakfast sandwiches, and lunch items. The company also licenses its trademarks through licensed stores, and grocery and foodservice accounts. The company offers its products under the Starbucks Coffee, Teavana, Seattle's Best Coffee, Ethos, Starbucks Reserve, and Princi brands. Starbucks Corporation was founded in 1971 and is based in Seattle, Washington.

Starbucks Bull Case

Here are some ways that investors could benefit from investing in Starbucks Co.:

  • Starbucks Co. shares recently gained 1.54% to close at $92.29, outperforming the broader market which dipped on the same day, a move driven by the company's public denial of takeover rumors that removed a potential strategic distraction and allowed investors to refocus on core operating performance.
  • The company demonstrated strong earnings resilience by beating consensus estimates in its most recent quarterly report, posting earnings per share of $0.85 against an expected $0.66, which signals that management is effectively executing its turnaround strategy despite macroeconomic headwinds.
  • Starbucks Co. offers a dividend yield of 2.66%, providing a steady income stream for investors, a feature that remains attractive even as the stock trades below its 52-week high of $110.51, suggesting potential for capital appreciation alongside income.
  • With a beta of 0.98, the stock exhibits market-like volatility, making it a relatively stable holding for investors seeking exposure to the consumer discretionary sector without the extreme price swings associated with higher-beta growth stocks.
  • Recent institutional activity, including new stakes purchased by major entities like Bank of America Corp DE and The Manufacturers Life Insurance Company in the second quarter, indicates that large investors are accumulating positions, which can provide a supportive floor for the stock price.

Starbucks Bear Case

Investors should be bearish about investing in Starbucks Co. for these reasons:

  • The stock carries a high price-to-earnings ratio of 53.04, which is significantly elevated compared to many peers in the restaurant sector, implying that investors are paying a premium for future growth that may not materialize if the company's revenue growth remains sluggish, as seen in the 1.4% year-over-year revenue decline in the latest quarter.
  • CEO Brady Brewer has consistently sold shares under a pre-arranged trading plan, including a recent sale of 2,229 shares in September, which may signal a lack of confidence in the stock's near-term upside or a desire to diversify personal holdings away from the company.
  • Short interest remains notable with approximately 41.97 million shares shorted as of the latest record date, representing about 3.68% of the float, indicating that a significant portion of the market is betting against the stock's performance, which can lead to volatility if short sellers continue to add to their positions.
  • The company's return on equity was negative at 34.10% in the most recent quarter, suggesting that the firm is not efficiently generating profits from shareholder capital, a metric that is critical for long-term value creation and may deter value-oriented investors.
  • Despite the recent earnings beat, the company's revenue has shown signs of stagnation or decline in recent periods, with the latest quarter showing a 1.4% drop compared to the same period last year, raising concerns about the sustainability of its top-line growth and market share in a competitive landscape.

Starbucks: Indicators Turns Bearish, New Lows in Sight

Written By Thomas Hughes on 5/2/2024

Starbucks, coffee company and coffeehouse chain,

Starbucks (NASDAQ: SBUX) is one of many consumer-forward businesses that indicate weakness in the consumer. McDonald’s (NYSE: MCD) and Kraft Heinz (NASDAQ: KHC) revealed tepid results in fast food and consumer staple products, suggesting the squeeze is real and consumer health flagging. The difference is that Starbucks’ results were so far below expectations that they altered the full-year outlook, which is likely not an isolated incident. 

Starbucks may be the only one to show significant contraction this quarter, but who will be added to the list next, after another ninety days of “higher for longer” policy and 4% consumer inflation? The FOMC may be on track to cut rates, but rate cuts are unlikely before September. Consumers will continue to feel the pinch and cut back on their spending. Lattes got cut from budgets in Q1, a trend likely to continue; what business will be next?

Starbucks Builds Leverage, Demand Slows

Starbucks struggled in Q1, a recurring theme across segments and industries. The company wasn’t expected to post robust results, but the $8.56 billion in revenue is down 1.8% compared to last year and 650 basis points shy of the consensus. Globally, comps are down 4% and offset by a 3% increase in store count, 364 of which were added in Q1. 

Starbucks comps are down on a 6% decline in traffic, a worrisome detail, offset by a 2% increase in ticket average. The ticket average is up on higher prices. US comps, the largest market, are down 3%, with international down 6%. China, the 2nd largest market, is down 11% and is 18% of the net. 

The margin news is also unfavorable to shareholders today. The company logged triple-digit basis point declines in the GAAP and adjusted operating margin to leave adjusted and GAAP earnings at $0.68. That is shy of the consensus by $0.12 and down 8%, more than quadrupling the top-line contraction. 

The weakness in Q1 was compounded by the guidance, adding to the stock’s steep decline. The company cut its outlook for revenue, comp store growth, store count growth, and margin. The company sees revenue growing in the low single-digits compared to high-single to low-double, with US comps running near 1% and margin flats instead of improving.  Bottom line, the bottom line outlook for this year is garbage and will be revised sharply lower. If this becomes a broader trend among discretionary/consumer names, it will undercut the outlook for S&P 500 earnings and broad market support.

Analysts Cut Targets For Starbucks: A Deep Value Opportunity? 

Analysts rate Starbucks at a consensus Hold and see it gaining a 40% upside on average. However, the post-release activity includes at least one downgrade and numerous price target reductions; Marketbeat tracks no price target increases. The new targets are below the consensus, suggesting an upside but less than 40%. However, the stock is trading below the low end of the range, which is unchanged, indicating a deep-value opportunity. The question is how much deeper the stock may fall and how long to wait until it rebounds. 

The technical action is strongly bearish, creating a gap and a large red candle. The market will likely fall from the day’s lows, but support is near. Support targets near $70, and the 2022 lows should be strong enough to keep the market from falling further. If not, this stock could fall to the pandemic lows near $56. Assuming the market rebounds from critical support or higher, the first target for significant resistance is near $80 to $82, with numerous potential targets for resistance up to the $110 region. 
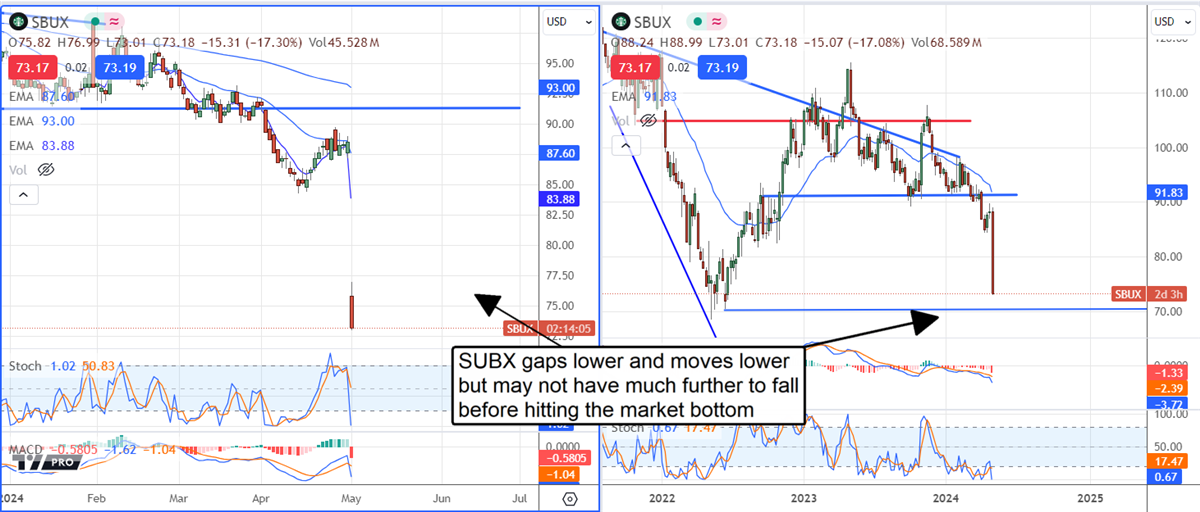
SBUX stock chart

Recent News