Stock of the Day

April 7, 2026

Honeywell International (HON)

$213.32
+$3.34 (+1.6%)
Market Cap: $66.55B

About Honeywell International

Honeywell International Inc. engages in the aerospace technologies, building automation, energy and sustainable solutions, and industrial automation businesses in the United States, Europe, and internationally. The company's Aerospace segment offers auxiliary power units, propulsion engines, integrated avionics, environmental control and electric power systems, engine controls, flight safety, communications, navigation hardware, data and software applications, radar and surveillance systems, aircraft lighting, advanced systems and instruments, satellite and space components, and aircraft wheels and brakes; spare parts; repair, overhaul, and maintenance services; and thermal systems, as well as wireless connectivity services. Its Honeywell Building Technologies segment provides software applications for building control and optimization; sensors, switches, control systems, and instruments for energy management; access control; video surveillance; fire products; and installation, maintenance, and upgrades of systems. The company's Performance Materials and Technologies segment offers automation control, instrumentation, and software and related services; catalysts and adsorbents, equipment, and consulting; and materials to manufacture end products, such as bullet-resistant armor, nylon, computer chips, and pharmaceutical packaging, as well as provides materials based on hydrofluoro-olefin technology. Its Safety and Productivity Solutions segment provides personal protective equipment, apparel, gear, and footwear; gas detection technology; custom-engineered sensors, switches, and controls for sensing and productivity solution; cloud-based notification and emergency messaging; mobile devices and software; custom-engineered sensors, switches, and controls; and data and asset management productivity solutions. Honeywell International Inc. was founded in 1885 and is headquartered in Charlotte, North Carolina.

Honeywell International Bull Case

Here are some ways that investors could benefit from investing in Honeywell International Inc.:

  • The stock is currently trading at $209.98, which is significantly below the average analyst price target of $249.60, suggesting substantial potential upside for investors who believe the market is undervaluing the company's long-term prospects.
  • Honeywell International Inc. recently launched Forge Cognition, an agentic AI and simulation platform developed with NVIDIA and Dell Technologies, which uses digital twins and AI agents to manage energy, maintenance, and safety across industrial facilities, reinforcing the company's strategy to expand higher-value software and automation offerings.
  • The company secured an approximately $300 million contract for process technologies and digital solutions for a planned 700,000-barrel-per-day refinery project, providing longer-term revenue visibility and supporting the growth of its process technology and digital businesses.
  • With a dividend yield of 3.39% and a P/E ratio of 8.12, the stock offers an attractive income stream and a low valuation multiple compared to many peers, which may appeal to value-oriented investors seeking stability and cash flow.
  • Institutional interest remains strong, with 75.91% of the stock owned by hedge funds and other institutional investors, and recent new positions were opened by firms such as Studio Investment Management LLC and DMC Group LLC, indicating continued confidence from professional investors.

Honeywell International Bear Case

Investors should be bearish about investing in Honeywell International Inc. for these reasons:

  • The stock has experienced a significant year-to-date decline, with the 52-week high at $261.24 and the current price of $209.98 reflecting a substantial drop, which may indicate ongoing investor concerns about growth and execution despite the low valuation.
  • Several major financial institutions have recently lowered their price targets, including Mizuho cutting its target from $265.00 to $255.00 and Royal Bank of Canada reducing its target from $293.00 to $270.00, signaling a more cautious valuation outlook among key analysts.
  • The consensus rating for the stock is currently "Hold," with twelve analysts issuing a Hold rating compared to thirteen Buy ratings and one Sell rating, suggesting that the market is divided on the stock's near-term potential and that the risk-reward profile may not be compelling for all investors.
  • CEO Kenneth West sold 316 shares of the stock on August 3rd, 2026, at an average price of $245.47, which, while a small transaction, may be interpreted by some investors as a signal of reduced insider confidence or personal financial planning that could influence sentiment.
  • The company's Q3 2026 earnings are expected to show declines in revenue and earnings due to segment weakness and rising costs, which could pressure the stock price further if the results do not meet the already lowered expectations of analysts and investors.

5 Spin-Off Stocks That Could Reward Patient Investors in 2026

Written By Thomas Hughes on 3/26/2026

FedEx delivery van on suburban street, illustrating logistics business amid corporate spin-off strategy.

Spin-offs are a great tool for businesses, helping them rationalize ongoing business, focus on growth, and unlock shareholder value. The key question is whether a separation changes how investors might evaluate the original company, the new company, or both as standalone stories.

FedEx on Track to Deliver Value-Building Savings 

FedEx’s (NYSE: FDX) spin suggests both the original and new companies are buyable. The spin-off separates the freight business from the core package delivery business, enabling both companies to trade at freer valuations. The critical takeaway for potential investors in the freight company is that it may trade at a 50% or higher premium to the original. The hurdle for the freight business is 2026 headwinds, including tepid demand, margin pressure, and expansion costs.
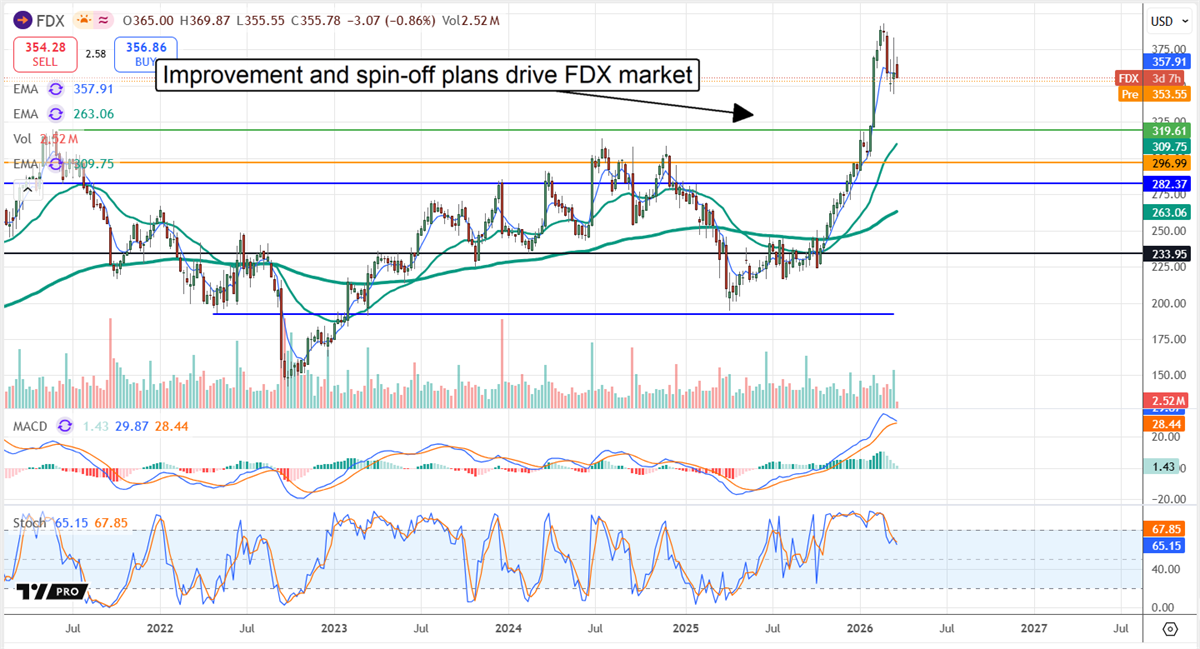
FDX stock chart displaying a market driven by improvement and spin-off plans.

Takeaways for investors in the original FDX include improvements in operational quality, cash flow, and the reliability of capital returns. FedEx’s capital return is significant, comprising dividends, dividend growth, and aggressive share buybacks. Buybacks reduced the count by more than 2.5% year-to-date as of the end of fiscal Q3 2026. Analysts are lifting price targets ahead of the split, indicating a Moderate Buy with potential to hit new highs by mid-year. 

KBR Split Enhances Focus, Unlocks Growth Avenues

KBR’s (NYSE: KBR) split and spin-off, scheduled for completion in the back half of 2026, aims to separate its Sustainable Technology Solutions business from its government business. The new company will comprise the Mission Technology Solutions group, which includes defense, security, and space applications. Among the reasons for this spin is the unlocking of value; the spinco may experience a 100% to 200% price gain based on the original’s 9X multiple. Defense specialists such as Lockheed Martin (NYSE: LMT), Northrop Grumman (NYSE: NOC), and RTX (NYSE: RTX) trade at well over 20 times earnings. 
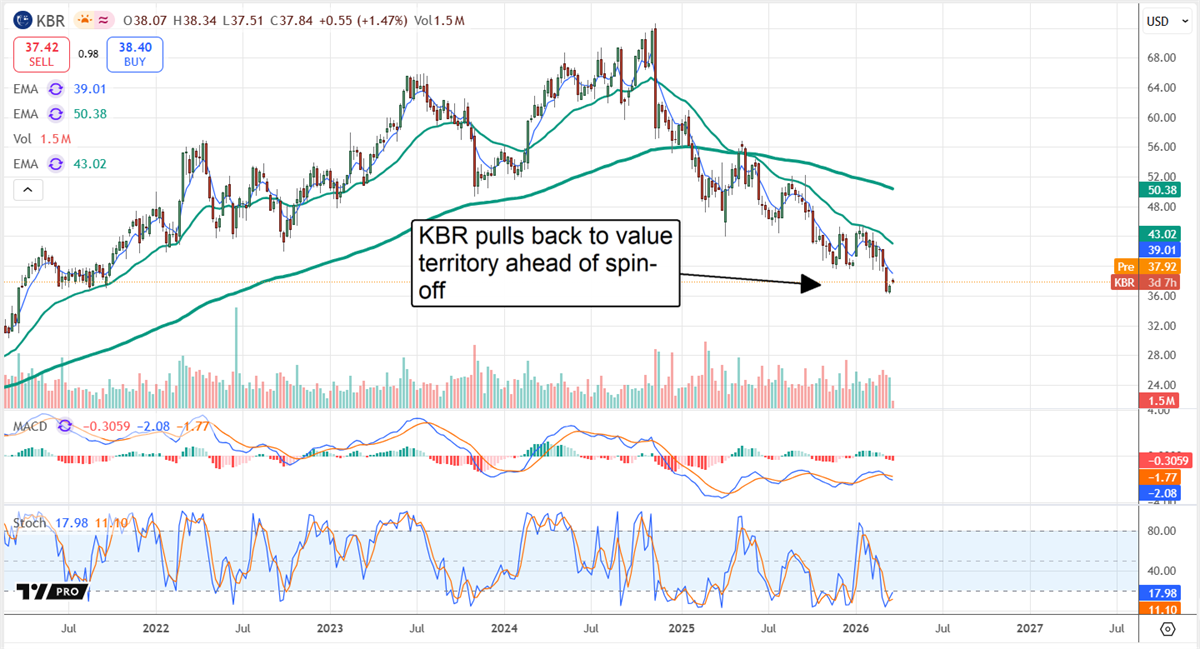
KBR stock chart pulling back to value territory ahead of spinoff.

While the spinco will focus on defense contracts and execution of its massive backlog, the ongoing business will focus on higher margin sustainable energy technologies. The leaner company will benefit from speedier decision-making and financial flexibility, enabling it to continue investing in its future. Analyst revisions are mixed in 2026, but the trend is stable, leaving the rating at Hold and the consensus price target forecasting about a 50% upside. 

Medtronic to Spin-Off High-Growth Diabetes Unit

Medtronic (NYSE: MDT) plans to spin off its high-growth diabetes unit later this year, a move that, at face value, seems counterintuitive. However, the diabetic unit is a consumer-oriented business while the core is business-to-hospital, presenting challenges for the combined company. The result will be a pure-play diabetic equipment and supply company, able to compete effectively in its high-growth market, and with the potential for takeover.
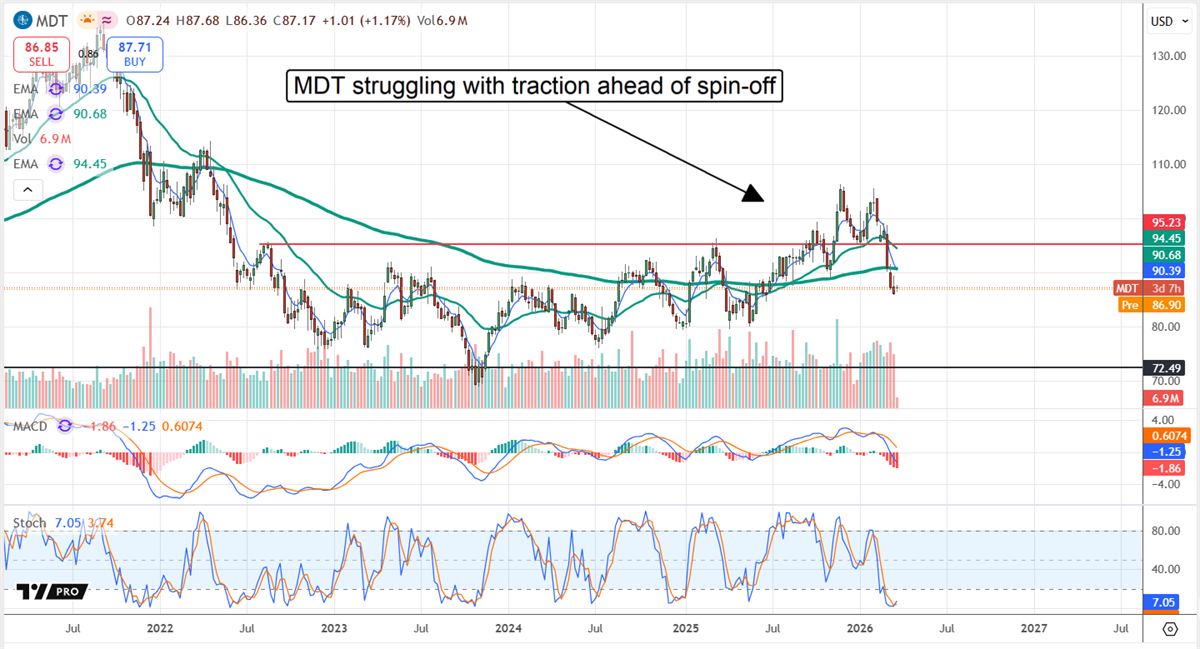
MDT stock chart displaying a market struggling with traction ahead of its spin-off.

The remaining company will focus on high-growth, higher-margin businesses such as cardiovascular and robotic surgery. Robotic surgery is the future of medicine, with leaders such as Intuitive Surgical (NASDAQ: ISRG) sustaining double-digit growth rates and steadily improving operational quality. Twenty-six analysts rate this stock as a Moderate Buy, coverage is increasing, the sentiment is firm, and the consensus price target forecasts more than 25% upside as of late March. 

Keurig Dr Pepper: Grows to Split, Unleashes Global Powerhouses

Keurig Dr Pepper (NASDAQ: KDP) has struggled for years as strengths and weaknesses in the soda business offset strengths and weaknesses in the coffee business. Now, the company plans to make another coffee acquisition, then spin the coffee bundle into a pure-play for investors. The combined business will experience supply chain efficiencies and unlock growth opportunities, specifically in the high-margin coffee pod industry. 
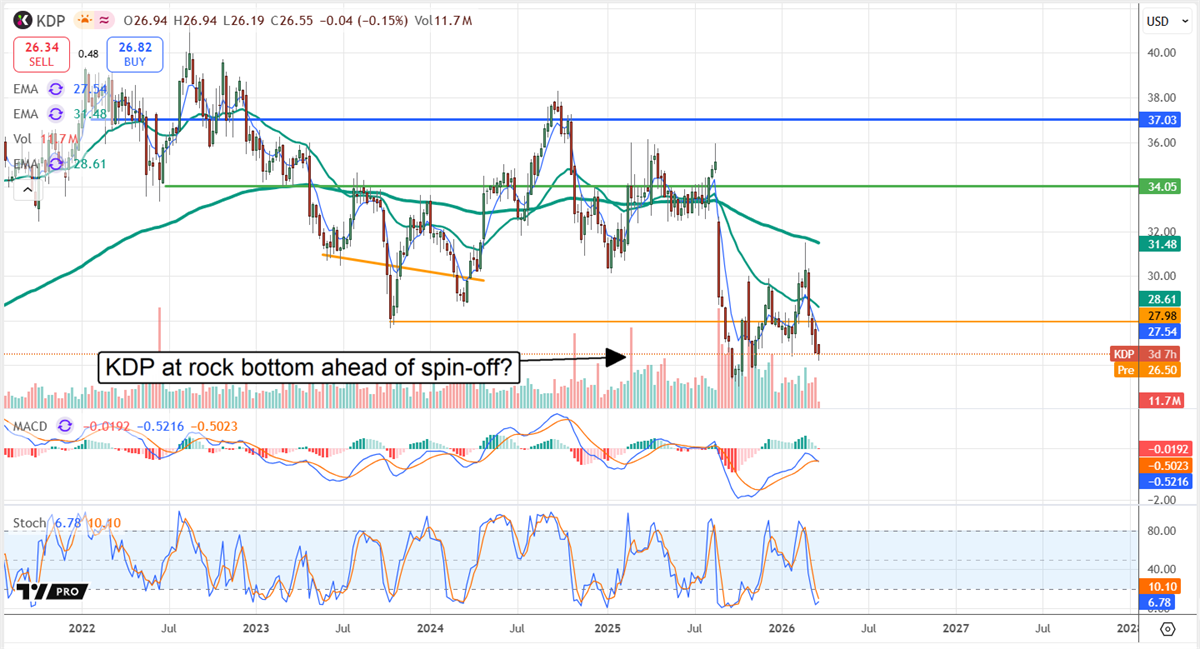
KDP chart showing the stock at rock bottom ahead of its spin-off.

The ongoing business will be a soda-and-beverage pureplay, unencumbered by coffee-specific issues, with an enhanced financial profile. It will be able to focus on its higher-margin businesses and growth, including acquisitions, and is expected to be completed in April. Analysts are bullish on this stock, rating it a Moderate Buy and raising price targets ahead of the spin-off. The consensus price target reported by MarketBeat forecasts close to 35% upside, while the high-end of price targets adds double digits. 

Honeywell Splits to Enhance Focus With 2 Pureplay Businesses 

Honeywell (NASDAQ: HON) aims to split its aerospace business into a more focused pure-play unit. It will service defense and commercial contracts, execute on a record backlog, and improve cash flow while the original business focuses on industrial automation. Industrial automation is the linchpin of the Industrial Revolution 4.0 and the nexus of Internet of Things (IoT), robotics, and AI. The spin allows it a more flexible financial position, enabling strategic acquisitions to sustain growth long-term. 
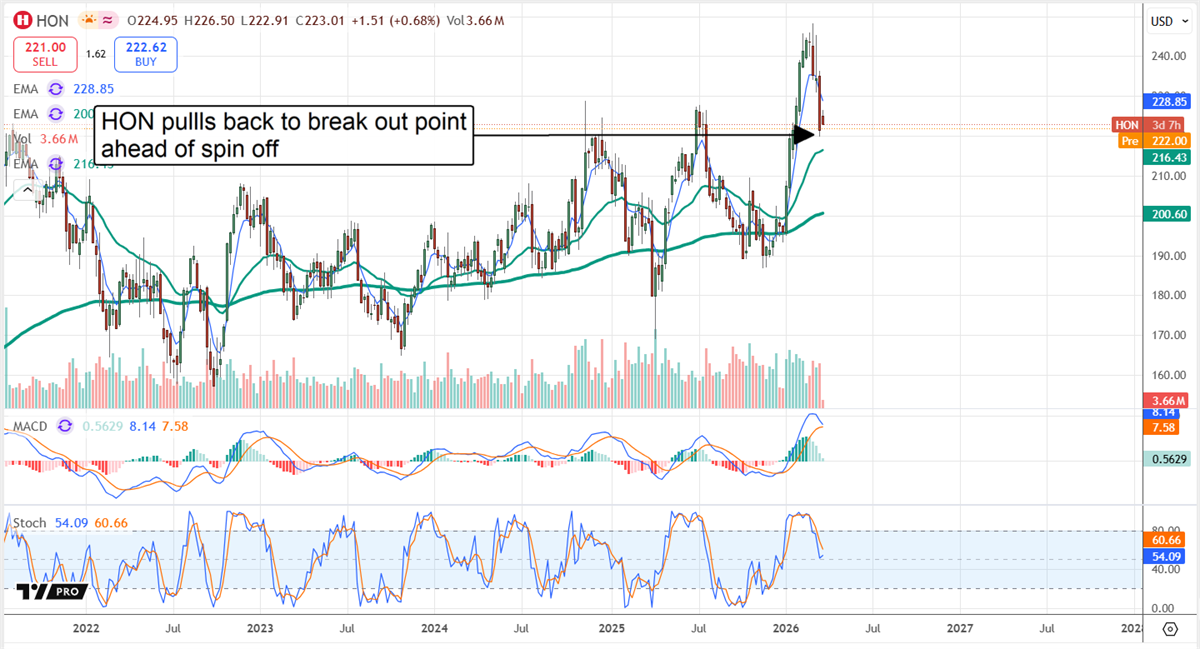
HON chart displaying the stock pulling back to a break out point ahead of its spin-off.

Analyst trends suggest the group is most bullish on this stock. MarketBeat’s data reflects swelling coverage, firming sentiment pegged at Moderate Buy, and an uptrend in the price targets. Consensus forecasts call for a 10% upside in late March, and the trends point to the high end and are likely to remain strong through year-end. 

Recent News