While the debate over how high interest rates will go rages on, the FOMC almost certainly won't cut rates anytime soon. The takeaway for investors is that the “new normal” of higher-for-longer, which took effect two or three years ago, is now normal and unlikely to change. For investors, this means refocusing on high-quality, rate-resistant stocks that deliver value.
Rate-resistant stocks share a few qualities that drive positive stock price performance over time, whether the FOMC is hiking or cutting rates, including healthy balance sheets, pricing power, and reliable cash flow. Low- or fixed-rate debt insulates companies from rising borrowing costs, while strong cash positions provide yield on deposits. Pricing power comes from brand strength and market position, which typically entails essential goods and services—dailies and necessities people and businesses can’t live without. This enables the ability to pass through higher costs and maintain margins, which is critical.
Reliable cash is what matters. Rate-resistant stocks can drive cash flow in all cycles and, more importantly, free cash flow for reinvestment and capital returns. Capital returns often include dividends and share buybacks, both of which can drive investment. In this light, many Dividend Champions and Dividend Kings would qualify as inflation-resistant, having proven their ability to sustain cash flow and capital returns through business cycles.
JPMorgan Chase & Co: Benefiting From Structural Tailwinds
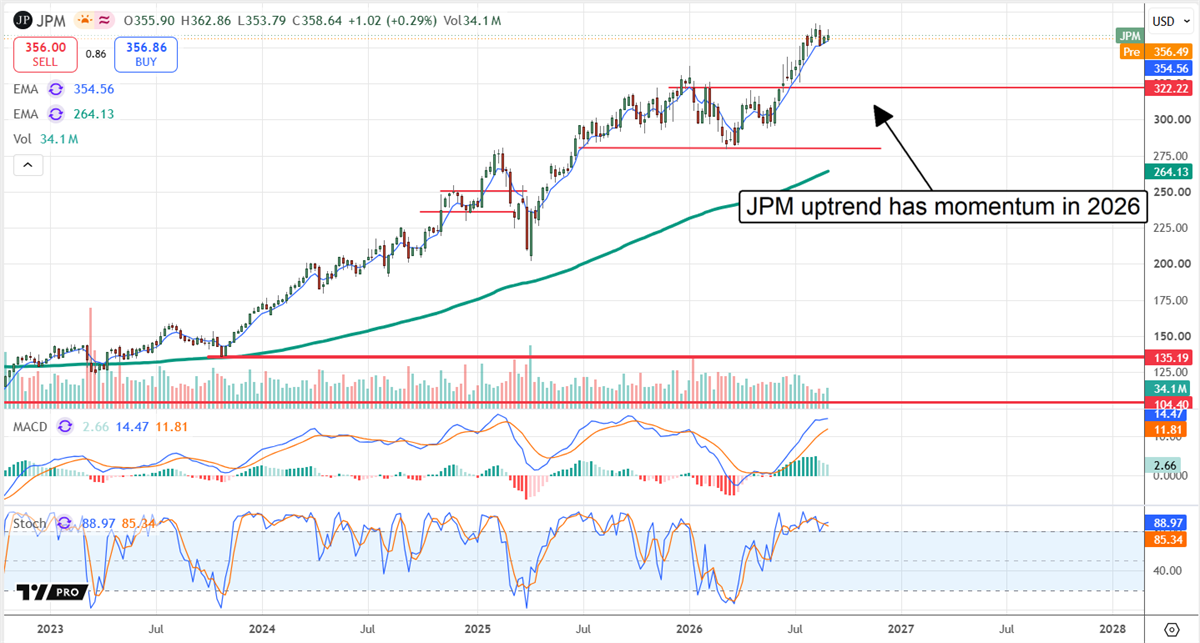
While higher rates may impair JPMorgan’s (NYSE: JPM) business traffic, they are good news for its cash flow and balance sheet. Higher rates mean higher margins, improved cash flow from investments and net interest income (NII) growth. NII growth underpins its ability to sustain top-tier financial health and substantial capital returns.
JPM yields approximately 1.7% annually as of early September, paying out less than 30% of its annualized earnings and on track to sustain annual distribution increases.
As it stands, JPM's dividend has increased for 15 consecutive years, making it a Dividend Achiever on track for Champion status.
JPMorgan’s growth outlook isn’t robust but remains positive, expected to sustain a mid- to low-single-digit pace over the next five to 10 years while maintaining margins.
The 10-year forecast suggests the stock trades at a deep value, approximately half the current-year valuation, setting the stage for a triple-digit stock price increase over time.
Analysts and institutions express confidence in the outlook, with 28 analysts rating it a consensus Moderate Buy, a Buy-side bias to the data, an uptrend in price targets, and institutions accumulating in 2026.
Exxon Mobil: Well Positioned, and Higher Oil Prices, Too!
Exxon Mobil (NYSE: XOM) is a rate-resistant stock because its foresightful management takes a prudent, cash-conserving approach to the business.
While it could deliver windfall capital returns as oil prices drive margin strength, it doesn’t, choosing instead to preserve financial health and prepare for when oil prices aren’t as favorable.
As a result, Exxon Mobil maintains a healthy balance sheet and capital-return capacity, including reliable dividends and share buybacks.
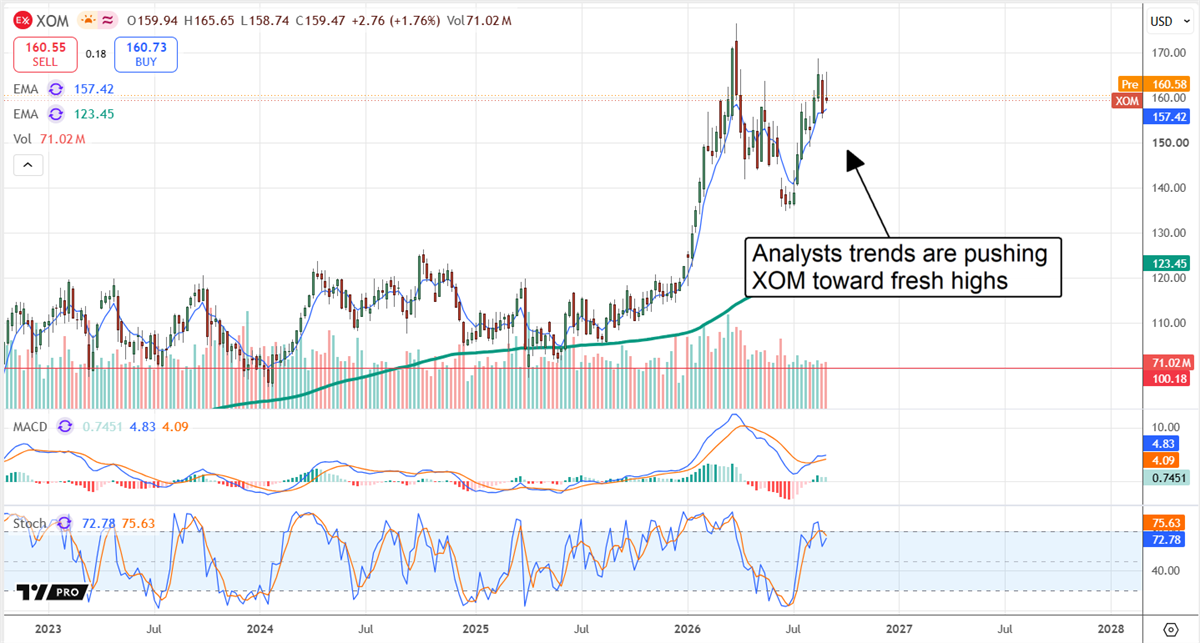
The dividend, yielding about 2.6% in early September, isn’t the highest in the energy sector, but it is incredibly consistent, and the distribution grows annually.
Exxon Mobil has increased its payment for over 40 consecutive years, putting it on track to be crowned a Dividend King before 2035 (a catalyst for ownership, attracting institutional and retail buy-and-hold investors).
Analysts rate XOM a consensus Hold, with a 45% Buy-side bias among 22 tracked analysts. The price-target trend is bullish, and the institutional group is accumulating.
Alphabet: Defying Logic in an AI-Driven World
Alphabet (NASDAQ: GOOGL) is not unique, but unlike most other mega-cap tech companies, it has a fortress balance sheet, a massive cash pile, and a nearly unmatched capacity to self-fund growth.
Its dominance in search—an estimated 90% market share—anchors a highly profitable advertising business that throws off enormous cash.
Self-funding growth is a key detail in 2026, as Alphabet is a top-3 hyperscaler central to the data center buildout, and is accelerating capital expenditure (CapEx) plans quarterly. While risks remain, its surging backlog helps to mitigate them, pointing to sustained, high-level growth and margins over time.
Alphabet’s dividend is not robust, only a token meant to enable broader investment among institutional groups, but buybacks are more substantial.
The caveat for 2026 is that buybacks are effectively halted while the AI buildout is underway, but they are expected to resume as the front-loaded CapEx converts to revenue and cash flow.
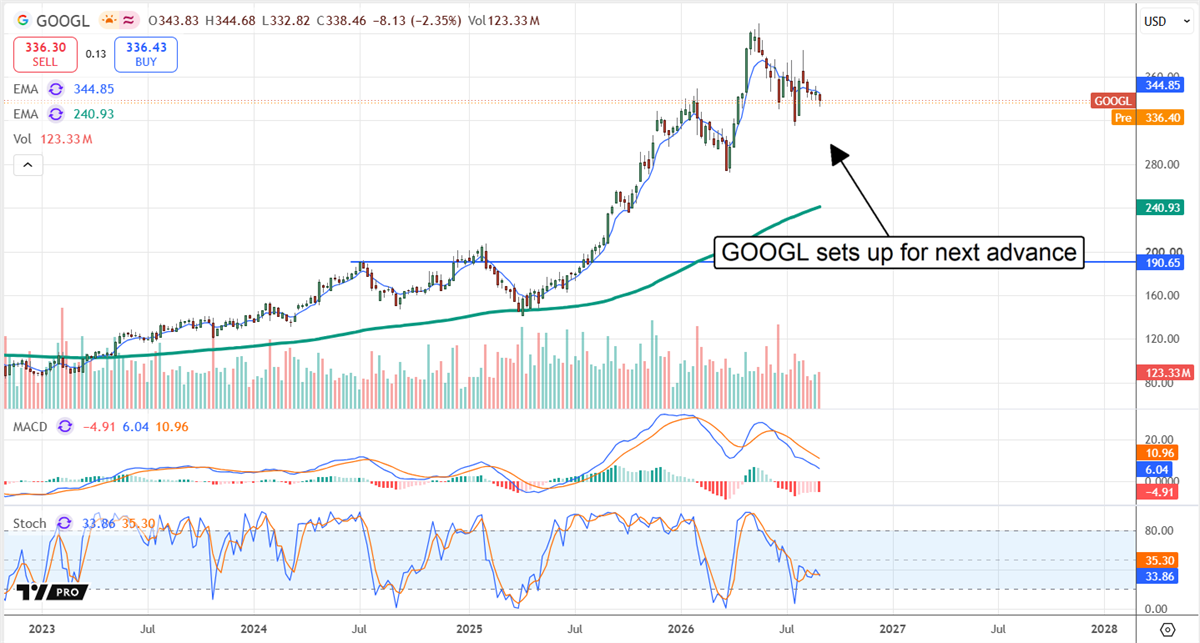
Until then, analyst trends are bullish, with 54 analysts rating GOOGL a consensus Buy, sentiment firming, and price targets trending higher. Consensus forecasts more than 20% upside from early Q3 support levels, with revisions pushing toward the high end, implying another high-teens advance.