onsemi’s (NASDAQ: ON) all-stock bid to acquire Synaptics (NASDAQ: SYNA) initially depressed the share price, but now things are different. The massive share price decline undercut the value of the all-stock Synaptics bid, enabling a competing suitor to enter the mix.
Faced with a superior offer, onsemi made the nimble pivot to an all-cash deal, securing its bid and accelerating a major transformation—from component provider to end-to-end physical AI systems original equipment manufacturer (OEM)—and at better terms.
Why is the move so brilliant? Four key reasons: dilution, price tag, accretion, and ownership. The original deal was all stock, meaning onsemi would dilute its shares, the ultimate cause of its share price plunge. The new deal is all cash, which means no dilution or overhang and improves the equation on price, accretion, and ownership.
The price tag is now $5.7 billion, down 18.57% from the initial offer, with the share count unchanged. More importantly, the revised structure is expected to be immediately accretive to earnings upon closing, compared with accretion within 18 months under the original agreement. Finally, ownership: onsemi shareholders retain 100% ownership, sharing no part of the business with Synaptics’ investors, who will receive $123 per share, a nearly 35% premium to the 150-week exponential moving average price.
onsemi’s Metamorphosis Is Nearly Complete
onsemi’s transition is significant, and the metamorphosis is nearly complete. While hurdles remain, they are low, given the Federal Trade Commission’s Early Termination Notice. It effectively indicates that the deal does not raise significant competition concerns and can close more quickly than usual. As it stands, the deal is set to close by mid-next year, setting the stage for onsemi’s next phase.
What Synaptics brings to onsemi complements its already robust portfolio of power control and sensing devices, adding wireless connectivity, neural processing units (NPUs), and the Astra AI platform. Product highlights include ultra-low power consumption, edge AI without cloud backup, and an easy-to-use open-source framework.
Wireless connectivity spans the range, enabling autonomous machines to access local networks and Wi-Fi. More importantly, Synaptics’ industry-leading NPUs solve a critical hurdle—obsolescence—through a dual-brain approach developed in deep partnership with Alphabet (NASDAQ: GOOGL).
Synaptics’ contribution handles on-site tasks such as sensing, while Alphabet’s contribution is programmable, allowing it to adapt to inevitable code changes and upgrades. Together, onsemi and Synaptics cover the four pillars of physical AI—power, sensing, connected compute, and control—in a single package, making it a base layer developers can build on.
onsemi: Critical to NVIDIA’s Long-Term Plans
onsemi is already central to NVIDIA’s (NASDAQ: NVDA) near-term AI plans, providing essential power delivery technology that can handle the loads data centers require, especially next-generation 800VDC architectures. It is also pivoting alongside NVIDIA’s shift to focus on physical AI and robotics, positioning itself as the muscles and nervous system for NVIDIA’s AI brains. Execs estimate the opportunity at $6 billion by 2030, with onsemi capturing $900 in value per humanoid robot.
Analysts' trends reflect confidence in the shift, but they moderated their price targets following the initial acquisition announcement. It brought dilution and execution risks, and only one has been mitigated. Key details also include the consensus analyst rating and price target range, which show a 50% Buy-side bias within the Moderate Buy rating and room for a robust price recovery. The consensus price target offers minimal upside but is sufficient to trigger a technical reversal, while the high-end target suggests the potential to reach fresh all-time highs.
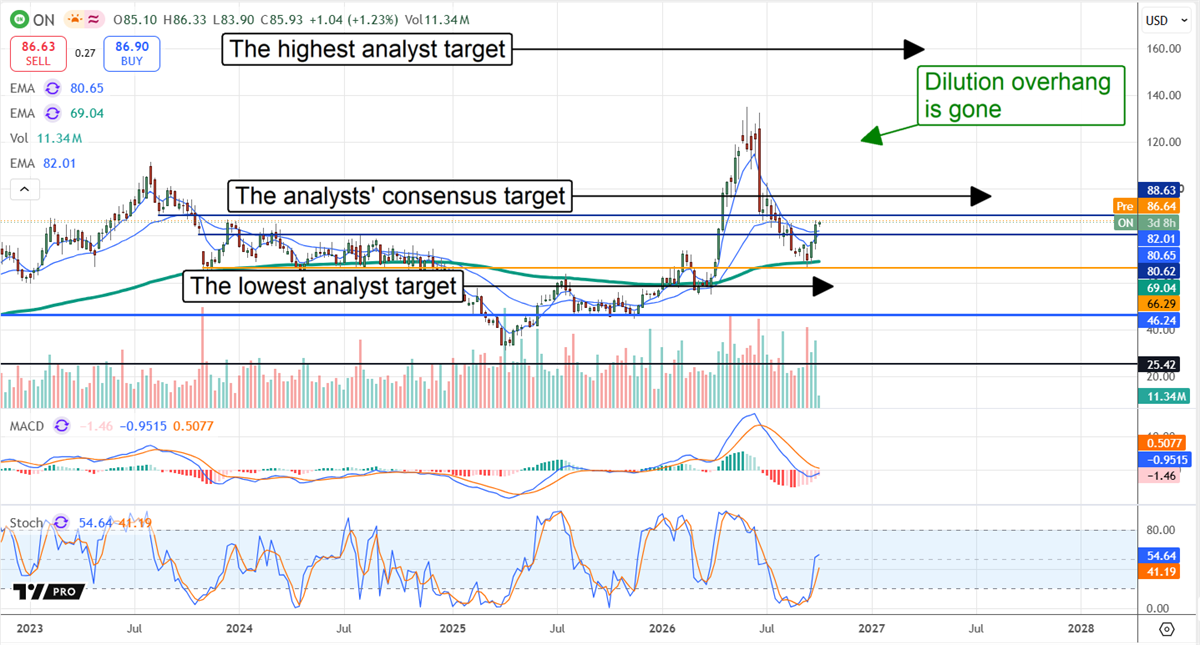
Institutions will be the deciding factor. The group owns nearly 98% of the stock, reflecting strong confidence, and underpins all major sustainable price movements. That includes the early 2026 price plunge, which helped set up today’s opportunity. While selling may continue, this market no longer has an overhang; instead, it has a catalyst that only needs to be executed to deliver immediate value gains. In this scenario, institutions might not revert to immediate accumulation, but they are likely to stop selling, freeing up price action.
The only bad news is that buybacks will pause. However, the new structure and onsemi's balance sheet mean it can finance the deal mostly with cash on hand. Morgan Stanley (NYSE: MS) has agreed to finance the remainder, up to $2.5 billion, an easy figure for onsemi to pay off. Execs target a 25% to 30% free cash flow margin, sufficient to pay off the new debt within 18 to 24 months. What will remain is a larger, better-positioned company with greater revenue, cash-generating, and capital-returning capacity.