Stock of the Day

May 17, 2022

Cigna Group (CI)

$301.85
+$3.04 (+1.0%)
Market Cap: $79.72B

About Cigna Group

The Cigna Group, together with its subsidiaries, provides insurance and related products and services in the United States. Its Evernorth Health Services segment provides a range of coordinated and point solution health services, including pharmacy benefits, home delivery pharmacy, specialty pharmacy, distribution, and care delivery and management solutions to health plans, employers, government organizations, and health care providers. The company's Cigna Healthcare segment offers medical, pharmacy, behavioral health, dental, and other products and services for insured and self-insured customers; Medicare Advantage, Medicare Supplement, and Medicare Part D plans for seniors, as well as individual health insurance plans; and health care coverage in its international markets, as well as health care benefits for mobile individuals and employees of multinational organizations. In addition, it offers permanent insurance contracts sold to corporations to provide coverage on the lives of certain employees for financing employer-paid future benefit obligations. The company distributes its products and services through insurance brokers and consultants; directly to employers, unions and other groups, or individuals; and private and public exchanges. The company was formerly known as Cigna Corporation and changed its name to The Cigna Group in February 2023. The Cigna Group was founded in 1792 and is headquartered in Bloomfield, Connecticut.

Cigna Group Bull Case

Here are some ways that investors could benefit from investing in The Cigna Group:

  • The stock is currently trading at $298.94, which is significantly below the average analyst price target of $337.09, suggesting substantial upside potential as the consensus rating remains a Moderate Buy.
  • The company recently launched Health Sense, a new tool that links member data for personalized health management, which may drive further engagement and differentiate its services in the competitive healthcare market.
  • With a P/E ratio of 12.37 and a dividend yield of 2.20%, The Cigna Group offers an attractive valuation and income stream, supported by a payout ratio of 25.82% that leaves ample room for future dividend growth.
  • Institutional interest is strong, with the State of Alaska Department of Revenue increasing its stake by 192.9% in the third quarter and new positions opened by firms like Baker Ellis Asset Management and Sivik Global Healthcare.
  • The company demonstrated strong financial performance in the most recent quarter, beating consensus estimates with $7.78 in EPS and $71.56 billion in revenue, while maintaining a return on equity of 19.75%.

Cigna Group Bear Case

Investors should be bearish about investing in The Cigna Group for these reasons:

  • Short interest has been rising, with shares shorted increasing to 6,951,241 as of September 30, 2026, indicating growing bearish sentiment among traders who expect the stock price to decline.
  • Insider selling activity has been notable, with CEO David Cordani selling 201,878 shares in May 2026 and other insiders like Nicole Jones and Everett Neville also reducing their holdings over the past few months.
  • The company's current ratio of 0.76 and quick ratio of 0.76 suggest potential liquidity challenges, as current liabilities exceed current assets, which could impact its ability to meet short-term obligations.
  • Despite recent gains, the stock underperformed competitors on Wednesday, and analysts have noted that earnings risks remain, with some expecting a modest year-over-year decline in EPS for the upcoming quarter.
  • The Cigna Group has a debt-to-equity ratio of 0.68, which, while manageable, indicates a significant level of leverage that could constrain financial flexibility in a rising interest rate environment.

Follow The Money To Cigna

Written By Thomas Hughes on 5/10/2022
Follow The Money To Cigna

Cigna Falls On Strong Results, Analyst Upgrade 

It is times like this when following the money can give the best returns and the money is flowing toward Cigna (NYSE: CI). The company released a better than expected earnings report and raised its guidance sparking yet another wave of analysts upgrades and price target revisions. The latest includes at least 7 post-release commentaries with 7 price target upgrades and a new high price target as well. The high price target comes from Cowen which upgraded the stock to Outperform citing a number of catalysts for higher share prices. Among them are the stock's low valuation, an inflation-induced tailwind for managed healthcare, increasing market share, and an oncoming wave of biosimilar medications that will drive revenue for the pharmacy segment. 

Cowen’s price target of $329 is up from the previous $262 and compares very well to the Marketbeat.com consensus of $276. The consensus is only 5% above the current price action compared to almost 25% for Cowen’s target but the consensus is trending higher. Assuming the other 16 analysts following the stock see similar catalysts in store for the company there should be a few more upgrades and/or price targets at least. Until then, the stock is rated as a firm Buy by the analyst community. 

Cigna Beats And Raises Guidance For 2022

Cigna had a great quarter supported by strength across all business segments. The company reported $44.01 billion in net revenue for a gain of 7.4% over last year. The revenue also beat the Marketbeat.com consensus by 120 basis points and the good news does not end there. Moving down to the earnings, both segments contributed to earnings power and a YOY increase in margin. Digging a little deeper, a 180 basis point improvement in Cigna margin was offset by a 10 basis point contraction in Evernorth and both are better than expected. The  $6.01 in adjusted EPS is up from last year’s $4.73 and a company record. 

Turning to the guidance, the company raised its revenue target to at least $177 billion versus the consensus of $179 but it is the earnings guidance that has us interested. The adjusted EPS is expected to be at least $22.60 versus the consensus of $22.49 which is very good news for shareholders. The company is using its capital to buy back shares and pay a dividend that we view as growing. The company has only increased the distribution for two years but there is ample room in the numbers and earnings growth in the forecast. In our view, the company may not continue the 150% CAGR it has set but a healthy double-digit pace of increase is a reasonable expectation. 

The Technical Outlook: Cigna Might Have Just Peaked Out 

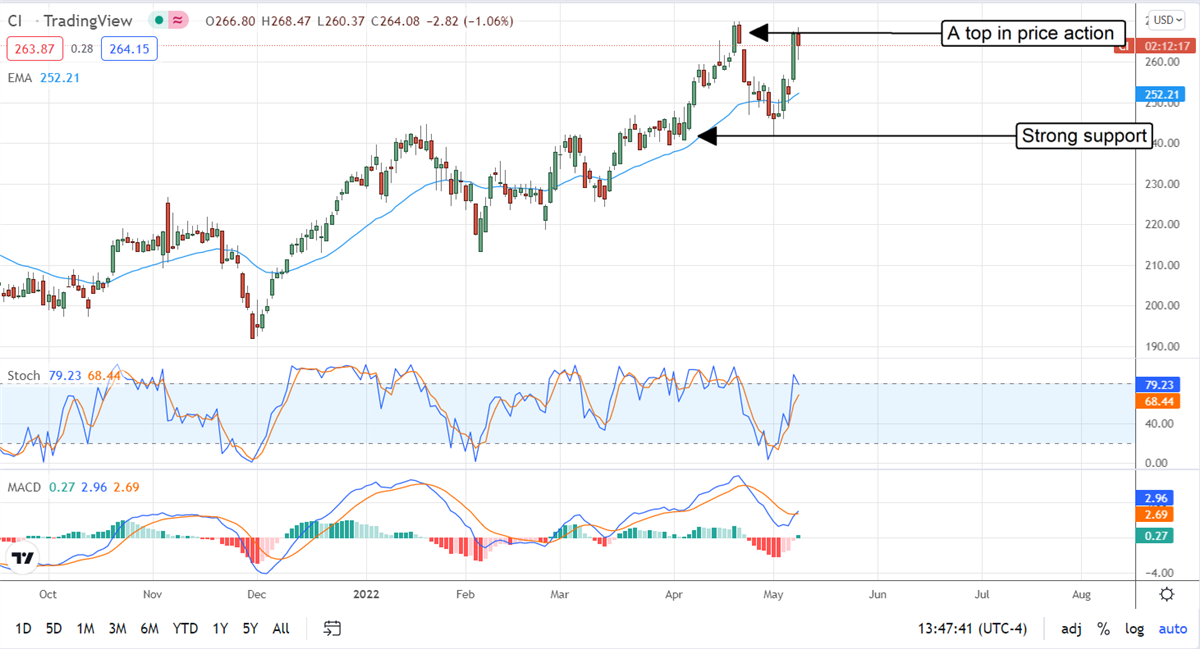
Institutional buying has been supporting Cigna's price action for years but the market may have just topped out. While the institutional activity has been net bullish over the last year it has been fairly balanced and not the support it has been in the past. This may keep price action from moving much higher in the near term but the long-term outlook is still bullish. In the near-term, price action may move sideways within the newly established range of $240 to $280 before setting a new high. The risk is that institutional support will fail and we don’t see that happening right now, not with the stock trading at 10X its earnings and yielding 1.7%. Longer-term, we see Cigna completing a consolidation at the current levels and then moving up to new highs as revenue, earnings, and capital returns grow. 
Follow The Money To Cigna And Be Rewarded 

Recent News