Stock of the Day

December 5, 2022

Medtronic (MDT)

$95.89
+$1.66 (+1.8%)
Market Cap: $120.53B

About Medtronic

Medtronic plc develops, manufactures, and sells device-based medical therapies to healthcare systems, physicians, clinicians, and patients worldwide. Its Cardiovascular Portfolio segment offers implantable cardiac pacemakers, cardioverter defibrillators, and cardiac resynchronization therapy devices; cardiac ablation products; insertable cardiac monitor systems; TYRX products; and remote monitoring and patient-centered software. It also provides aortic valves, surgical valve replacement and repair products, endovascular stent grafts and accessories, and transcatheter pulmonary valves; and percutaneous coronary intervention products, percutaneous angioplasty balloons, and products. The company's Medical Surgical Portfolio segment offers surgical stapling devices, vessel sealing instruments, wound closure, electrosurgery products, surgical artificial intelligence and robotic-assisted surgery products, hernia mechanical devices, mesh implants, gynecology and lung products, and various therapies to treat diseases, as well as products in the fields of minimally invasive gastrointestinal and hepatologic diagnostics and therapies, patient monitoring, airway management and ventilation therapies, and renal disease. Its Neuroscience Portfolio segment offers products for spinal surgeons; neurosurgeons; neurologists; pain management specialists; anesthesiologists; orthopedic surgeons; urologists; urogynecologists; interventional radiologists; ear, nose, and throat specialists; and systems that incorporate energy surgical instruments. It also provides image-guided surgery and intra-operative imaging systems and robotic guidance systems used in robot assisted spine procedures; and therapies for vasculature in and around the brain. The company's Diabetes Operating Unit segment offers insulin pumps and consumables, continuous glucose monitoring systems, smart insulin pen systems, and consumables and supplies. The company was founded in 1949 and is headquartered in Dublin, Ireland.

Medtronic Bull Case

Here are some ways that investors could benefit from investing in Medtronic plc:

  • Medtronic plc shares are currently trading at $91.61, which is significantly below the consensus price target of $102.92 set by twenty-eight brokerages, suggesting a potential upside of over 12% for investors who believe the market has undervalued the company's recent performance and strategic initiatives.
  • The company recently reported strong financial results for the quarter ending September 1, 2026, with actual earnings per share of $1.45 beating the consensus estimate of $1.39, and revenue of $9.756 billion exceeding the expected $9.546 billion, demonstrating robust operational execution and demand for its medical device portfolio.
  • Medtronic plc has successfully oversubscribed its exchange offer for MiniMed Group shares, a move that supports the company's strategy of separating its diabetes business to focus on its core medical-device operations, which may streamline management and improve long-term shareholder value.
  • With a dividend yield of 3.26%, Medtronic plc offers a competitive income stream for investors, providing a cushion against market volatility while the company continues to generate consistent cash flows from its established healthcare equipment and supplies business.
  • Recent analyst actions, including a price target increase to $110.00 by Bank of America and a "Buy" rating from BTIG Research, reflect growing confidence in the company's improving growth outlook and modest valuation relative to its peers in the healthcare sector.

Medtronic Bear Case

Investors should be bearish about investing in Medtronic plc for these reasons:

  • Short interest in Medtronic plc has surged significantly, with shares shorted increasing by 132.0% to 39,974,230 shares as of September 30, 2026, indicating that a substantial portion of the market is betting against the stock's future performance.
  • The stock has underperformed the broader market over the past year, declining by over 7% while the general market gained 17%, which may signal persistent structural challenges or a lack of investor confidence in the company's ability to drive growth in its current market environment.
  • Medtronic plc is facing significant capital expenditure pressures due to heavy spending on new technology areas such as robotics and cardiac ablation, which could impact near-term profitability and cash flow generation as the company invests in its future growth platforms.
  • Recent insider selling activity, including a sale of 1,483 shares by EVP Harry Skip Kiil in September 2026, may raise concerns among investors about the confidence of company executives in the stock's near-term trajectory.
  • The company's beta of 0.55 suggests lower volatility than the market, but this also means that Medtronic plc may not provide the same level of upside potential as higher-beta growth stocks during strong market rallies, limiting its appeal for aggressive growth investors.

S&P 500 Component DexCom Set For Further Price, Earnings Growth

Written By Kate Stalter on 11/13/2022

S&P 500 Component DexCom Set For Further Price, Earnings GrowthMedical device maker DexCom (NASDAQ: DXCM) has been trading in a fairly tight range recently, holding gains from the company’s third-quarter report in late October. 

The stock is up 16.33% in the past month. Even before the 19% gap-up following the earnings report, DexCom was already beginning to trend higher. 

In the past three months, DexCom has advanced 31.41%. It’s not the top performer within the medical device industry in the past 12 months, however. A large cap with top performance is Abiomed (NASDAQ: ABMD).

Smaller medical gear makers with outstanding price action include TransMedics Group (NASDAQ: TMDX) and Lantheus (NASDAQ: LNTH). Numerous small companies have also posted excellent price performance in the past year, making the entire sub-industry a rising leader within the broader healthcare sector. 

Fellow large caps Medtronic (NYSE: MDT), Stryker (NYSE: SYK), Boston Scientific (NYSE: BSX), and Edwards Lifesciences (NYSE: EW) are all underperforming DexCom. 

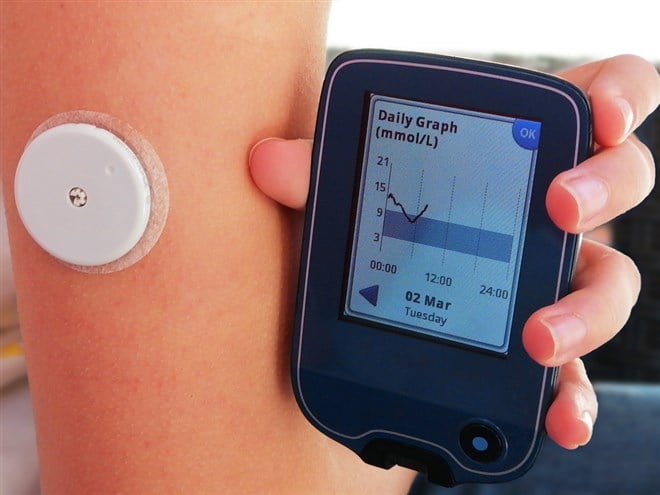
S&P 500 component DexCom makes glucose monitors for diabetes patients. That may sound like an established line of business without much need for innovation, but DexCom is busy creating more opportunities.

In the third quarter, the company earned 0.28 per share on revenue of $770 million. Those were gains of 27% and 18% respectively. DexCom beat views on both the top and bottom lines. 

Expanding Its Market

In the quarter, DexCom initiated the international rollout of its new sensor, G7. The product was launched in the United Kingdom, Ireland, Germany, Austria, and Hong Kong. It’s also received inclusion for healthcare reimbursement in several U.K. markets, which will likely help expand market share. 

The G7 is a wearable device that helps diabetics track blood-sugar levels. 

DexCom is focusing on making its continuous glucose monitors, known as CGMs, available to a bigger group of patients. Medicare and Medicaid rules may change, to allow patients needing one daily dose of insulin to get reimbursement for CGMs. If insurance companies follow the government's lead, and they typically do, that could be a boon for DexCom revenue. 

In the third-quarter earnings release, DexCom CEO Kevin Sayer also cited strong momentum in the company’s U.S. business. 

The company also updated its full-year revenue guidance. The company expects:

  • Revenue in a range of approximately $2.88 to 2.91 billion, which would be growth of 18% to 19%
  • Non-GAAP gross profit margin of approximately 64%
  • Non-GAAP Operating Margin of approximately 16%
  • Adjusted EBITDA Margin of approximately 25%

DexCom’s earnings growth has lagged others in its industry. The most recent quarter marked the first time in the past eight that the company posted earnings growth. Make no mistake: DexCom has been profitable every year since 2018, but earnings declined in 2021, to $0.66 per share, down from 2020’s $0.78 per share. 

Analysts See Earnings Growth Ahead 

For the full year 2022, Wall Street is eyeing earnings per share of $0.80, which would be a 21% increase. Next year, analysts expect net income of $1.11 per share, up 39%. 

MarketBeat analyst data for DexCom reveal a “moderate buy” rating on the stock, with a price target of $120.24, just 3.94% below where it’s currently trading. 

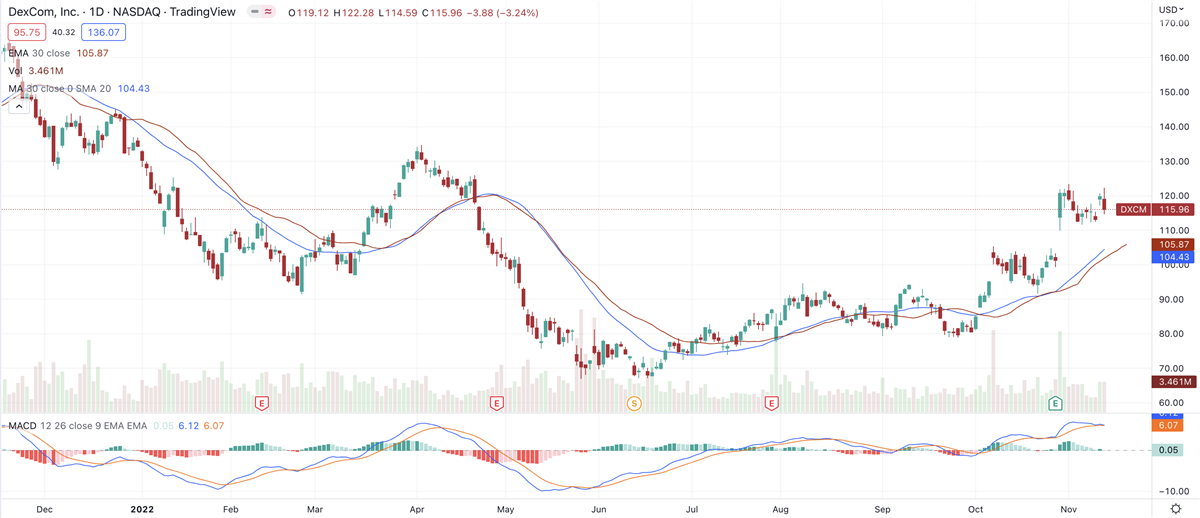
The DexCom chart shows that a rally attempt out of a cup-with-handle pattern broke down in April. The subsequent consolidation undercut the prior structure low, sinking to a nadir of $67.11 in mid-June when it began gradually etching the right side of the current consolidation. 

The stock closed Friday at $115.96, down $3.88 or 3.24%. It finished the session below its 10-day moving average, but the stock is squarely in buy range, now that it’s pulled back from its November 1 high of $123.36.
Recent News