Stock of the Day

January 18, 2023

Colgate-Palmolive (CL)

$92.61
-$0.17 (-0.2%)
Market Cap: $73.96B

About Colgate-Palmolive

Colgate-Palmolive Company, together with its subsidiaries, manufactures and sells consumer products in the United States and internationally. It operates through two segments: Oral, Personal and Home Care; and Pet Nutrition. The Oral, Personal and Home Care segment offers toothpaste, toothbrushes, mouthwash, bar and liquid hand soaps, shower gels, shampoos, conditioners, deodorants and antiperspirants, skin health products, dishwashing detergents, fabric conditioners, household cleaners, and other related items. This segment markets and sells its products under various brands, which include Colgate, Darlie, elmex, hello, meridol, Sorriso, Tom's of Maine, Irish Spring, Palmolive, Protex, Sanex, Softsoap, Lady Speed Stick, Speed Stick, EltaMD, Filorga, PCA SKIN, Ajax, Axion, Fabuloso, Murphy, Suavitel, and Soupline to a range of traditional and eCommerce retailers, wholesalers, and distributors. It includes pharmaceutical products for dentists and other oral health professionals. Its Pet Nutrition segment offers pet nutrition products for everyday nutritional needs under the Hill's Science Diet brand; and a range of therapeutic pet products to help nutritionally support dogs and cats in different stages of health under the Hill's Prescription Diet brand. This segment markets and sells its products through pet supply retailers, veterinarians, and eCommerce retailers. Colgate-Palmolive Company was founded in 1806 and is headquartered in New York, New York.

Colgate-Palmolive Bull Case

Here are some ways that investors could benefit from investing in Colgate-Palmolive:

  • Colgate-Palmolive shares are currently trading at $88.07, which is significantly below the consensus price target of $98.94 set by analysts, suggesting potential upside of over 12% for investors who believe the current valuation is too low.
  • The company recently reported earnings per share of $0.99 for the quarter ended July 31, 2026, which beat the consensus estimate of $0.947, demonstrating strong profitability and operational efficiency that supports the stock's fundamental value.
  • With a dividend yield of 2.43% and a recent quarterly dividend of $0.53 per share, Colgate-Palmolive offers a reliable income stream that is attractive to income-focused investors seeking stability in a volatile market.
  • The stock has a low beta of 0.33, indicating that it is less volatile than the overall market, which makes it a defensive investment that can help reduce portfolio risk during economic downturns.
  • Recent institutional activity shows strong buying interest, with funds like Sapient Capital LLC increasing their position by 240% and Horrell Capital Management Inc. adding 19,288 shares in the third quarter, signaling confidence in the company's future performance.

Colgate-Palmolive Bear Case

Investors should be bearish about investing in Colgate-Palmolive for these reasons:

  • The company's payout ratio is 84.13%, which is quite high and may limit its ability to reinvest in growth initiatives or absorb financial shocks, potentially constraining long-term earnings growth.
  • Recent insider selling activity is notable, with CEO Noel Wallace selling 161,021 shares and COO Panagiotis Tsourapas selling 10,000 shares in August 2026, which could signal a lack of confidence in the stock's near-term prospects.
  • Several analysts have recently lowered their price targets, such as Wells Fargo cutting its target from $95.00 to $90.00 and Piper Sandler reducing its target from $98.00 to $95.00, reflecting a more cautious outlook on the company's valuation and growth potential.
  • The stock is trading below its 50-day moving average of $89.16 and its 200-day moving average of $88.77, indicating that the short-term and medium-term momentum is negative and the stock may be in a downtrend.
  • Short interest has increased slightly, with shares shorted rising to 18,399,416 in September 2026 from 17,171,315 in August, suggesting that some investors are betting against the stock's price appreciation in the near term.

Conagra Brands: Another Reason To Go Long Consumer Staples In 2023

Written By Thomas Hughes on 1/5/2023

Conagra Brands: Another Reason To Go Long Consumer Staples In 2023

The Consumer Staples (NYSEARCA: XLY) sector has been a go-to sector for the last several years and Conagra Brands (NYSE: CAG) has just proven why it and they should still be on investor’s radars. The company is proving to be resilient in the face of rising costs and uncertain economic conditions. It is offering not only a value relative to its peers but a higher-than-average dividend that qualifies as “high yield” relative to the S&P 500 (NYSEARCA: SPY).

The takeaway here is that Conagra Brands just beat estimates on the top and bottom lines, showed tremendous pricing power and issued favorable guidance that has the market on the move and ready to tackle another new all-time high. 

Conagra Brands Guidance Has Shares At New Highs 

The Q2 results and guidance have price action in Conagra brands up more than 2.0% in premarket trading and at a new high. This is an almost 6-year high that dates back to well before the pandemic began, so is a very noteworthy move. The strength is driven by an 8.2% increase in revenue that outpaced the consensus by 100 basis points and was coupled with an increase in margins.

Revenue strength was driven by gains in all segments, led by a 14% increase in the retail snacks business, which is good news for Pepsico (NASDAQ: PEP) when it reports. On an organic basis, sales are up 8.6% and offset by a 0.3% FX-related headwind. 

The best news is in the margin. The company increased its adjusted gross and operating margins to levels above the Marketbeat.com consensus estimates. The AGM expanded by 310 and the AOP by 237 to drive a 26.6% increase in the adjusted earnings. Adjusted earnings of $0.86 are up 26.6% YOY, and this strength is expected to continue into the 2nd half of the fiscal year. 

The guidance is moving this market as it includes increasing all metrics. The company is now expecting revenue growth from 7% to 8%, with an operating margin of 15.3% to 15.6%. This should drive adjusted EPS of $2.60 to $2.70, more than $0.10 above the consensus estimate at the low end of the range. Assuming the company’s momentum continues, this guidance may also be too low. 

Conagra Brands Is A High-Yield Value Stock 

Conagra Brands is offering value in the Consumer Staples trading at only 15X its earnings. This compares to the highest-valued stocks like Hormel (NYSE: HRL), The Clorox Company (NYSE: CLX) and Lamb Weston (NYSE: LW), which trade in a range of 25X to 35X. At the same time, the stock is yielding about 3.4%, which is among the highest yields in the group, and it is relatively safe.

The company’s leverage ratio is a low 0.8X, and it has a 4.2X coverage ratio, so there is cash flow on the books to cover the payment and extend the 3-year history of dividend increases to 4 and 5 years at the least.  Kraft Heinz (NASDAQ: KHC) is the only stock in the group with a higher yield and comparable value and it, too, is well-exposed to the retail snacks business. 

The analysts have yet to come out with commentary but rest assured it is on the way. The trend in sentiment is bullish so investors might expect to see the sentiment continue to firm and the consensus price target rise. As it is, the analysts have the stock set at a Firm Hold/Weak Buy with a price target now below the stock's trading level (but trending higher). 

The Technical Outlook: Conagra Brands Breaks Out 

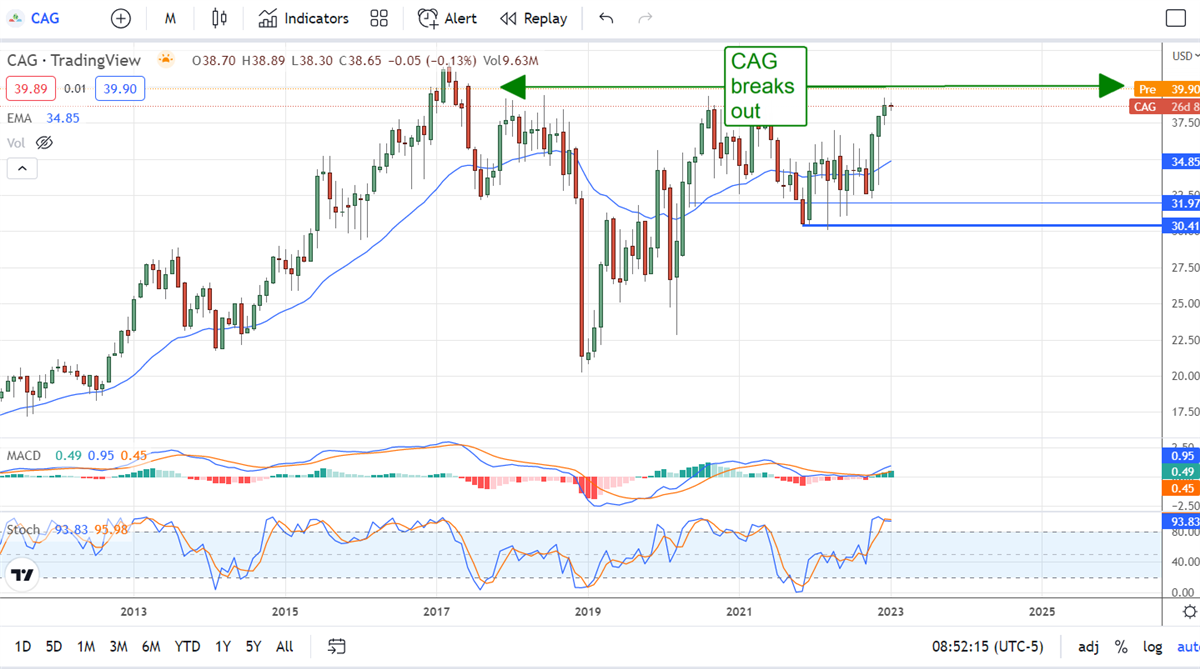
Conagra Brands is in the midst of a breakout that is best viewed with monthly data. The 3.3% price gain has it trading near $40 and at the highest since mid-2017. Assuming the market follows through on the signals and the news, this stock should at least retest the all-time highs if not break out to a new one. 
Conagra Brands: Another Reason To Go Long Staples In 2023

Recent News