Stock of the Day

February 20, 2023

Amgen (AMGN)

$432.49
-$1.54 (-0.4%)
Market Cap: $233.82B

About Amgen

Amgen Inc. discovers, develops, manufactures, and delivers human therapeutics worldwide. The company's principal products include Enbrel to treat plaque psoriasis, rheumatoid arthritis, and psoriatic arthritis; Otezla for the treatment of adult patients with plaque psoriasis, psoriatic arthritis, and oral ulcers associated with Behçet's disease; Prolia to treat postmenopausal women with osteoporosis; XGEVA for skeletal-related events prevention; Repatha, which reduces the risks of myocardial infarction, stroke, and coronary revascularization; Nplate for the treatment of patients with immune thrombocytopenia; KYPROLIS to treat patients with relapsed or refractory multiple myeloma; Aranesp to treat a lower-than-normal number of red blood cells and anemia; EVENITY for the treatment of osteoporosis in postmenopausal for men and women; Vectibix to treat patients with wild-type RAS metastatic colorectal cancer; BLINCYTO for the treatment of patients with acute lymphoblastic leukemia; TEPEZZA to treat thyroid eye disease; and KRYSTEXXA for the treatment of chronic refractory gout. It also markets other products, including Neulasta, MVASI, AMJEVITA/AMGEVITA, TEZSPIRE, Parsabiv, Aimovig, LUMAKRAS/LUMYKRAS, EPOGEN, KANJINTI, TAVNEOS, RAVICTI, UPLIZNA and PROCYSBI. The company serves healthcare providers, including physicians or their clinics, dialysis centers, hospitals, and pharmacies. It distributes its products through pharmaceutical wholesale distributors, as well as direct-to-consumer channels. The company has collaboration agreements with AstraZeneca plc for the development and commercialization of TEZSPIRE; Novartis Pharma AG to develop and commercialize Aimovig; UCB for the development and commercialization of EVENITY; Kyowa Kirin Co., Ltd. for rocatinlimab development and commercialization; and BeiGene, Ltd. for oncology products expansion and development. Amgen Inc. was incorporated in 1980 and is headquartered in Thousand Oaks, California.

Amgen Bull Case

Here are some ways that investors could benefit from investing in Amgen Inc.:

  • Amgen Inc. recently reported positive Phase 3 trial results for Tezspire in the treatment of eosinophilic esophagitis, a chronic inflammatory condition with limited approved options. In this study, nearly 70% of patients receiving the higher dose achieved remission at week 24, which could significantly expand the drug's addressable market and provide a new growth driver for the company's pipeline.
  • The stock is currently trading at $426.11, which is well above its 52-week low of $288.00 and approaching its 52-week high of $447.03. This price action reflects strong recent momentum, as the company has consistently beaten earnings estimates, such as the most recent quarter where it reported $6.29 in earnings per share against a consensus estimate of $5.62.
  • Amgen Inc. offers a dividend yield of 2.41%, with a recent quarterly payment of $2.52 per share. This provides a steady income stream for investors, supported by a payout ratio of 62.65%, which indicates the company is distributing a significant portion of its earnings to shareholders while maintaining a current ratio of 1.37 to manage its short-term liabilities.
  • Institutional interest in the stock has been increasing, with several funds raising their stakes in the third quarter. For example, First Citizens Bank & Trust Co. increased its position by 68.0% to 16,328 shares, and N10 Wealth LLC raised its stake by 62.6%, suggesting that professional investors are gaining confidence in the company's long-term outlook.
  • The company has received regulatory momentum, including a European Union authorization for Jascayd in July 2026. Additionally, Amgen Inc. is preparing for three Phase 3 studies of its obesity candidate MariTide in people with type 2 diabetes, which are expected to begin in 2026, positioning the company to compete in a high-growth therapeutic area.

Amgen Bear Case

Investors should be bearish about investing in Amgen Inc. for these reasons:

  • Insider sentiment appears cautious, as corporate insiders have reported seven open-market sales and no purchases during the past six months. For instance, SVP Rachna Khosla sold 2,000 shares in August 2026, and SVP Nancy Grygiel sold 2,970 shares in the same month, which may signal that company executives are taking advantage of the recent stock price appreciation to reduce their personal exposure.
  • Analyst consensus remains mixed, with a current rating of "Hold" and an average price target of $387.93, which is below the current stock price of $426.11. This suggests that many analysts believe the stock may be overvalued relative to its expected future earnings, as the current P/E ratio of 26.48 is higher than the consensus estimate for future growth.
  • The company carries a high debt-to-equity ratio of 4.44, indicating that Amgen Inc. relies heavily on debt financing relative to its shareholder equity. While the company has a quick ratio of 1.13, which shows it can cover short-term obligations, the high leverage could limit financial flexibility if interest rates remain elevated or if revenue growth slows.
  • Short interest in the stock has been rising, with 14,028,739 shares shorted as of September 30, 2026, representing 2.62% of the float. This increase from previous months suggests that some investors are betting against the stock, potentially due to concerns about valuation or competitive pressures in the biotechnology sector.
  • There is significant disagreement among analysts regarding the company's valuation, with some firms like Bank of America Securities maintaining a Sell rating. This divergence in opinion, combined with the fact that the stock has already risen significantly from its 52-week low, creates uncertainty about whether the current price fully reflects the company's future earnings potential.

Is Biotech Immunocore About To Make A 25% Price Move?

Written By Kate Stalter on 2/7/2023

Is Biotech Immunocore About To Make A 25% Price Move?

The biotech industry has stood out in recent months, with Immunocore Holdings PLC (NASDAQ: IMCR) among the group’s top price performers.

The industry is home to some large-cap heavyweights, including Amgen Inc. (NASDAQ: AMGN), Gilead Sciences Inc. (NASDAQ: GILD), Regeneron Pharmaceuticals Inc. (NASDAQ: REGN), Vertex Pharmaceuticals Inc. (NASDAQ: VRTX), and Moderna Inc. (NASDAQ: MRNA), among others. 

But less well-known companies, such as Exact Sciences Corp. (NASDAQ: EXAS), a top holding in Cathie Woods’ Ark Innovation ETF (NYSEARCA: ARKK), along with numerous small caps, have been notching strong rallies. 

U.K.-based Immunocore develops immunotherapies to treat cancer and infectious and autoimmune diseases. 

Its sole product currently on the market is Kimmtrak, a treatment for melanoma. However, Immunocore has six other potential drugs in its pipeline, drawing from the same technologies underpinning Kimmtrack. 

Developing More Treatments Using Existing Platform 

In addition to that compound, the biotech is working on six treatments using the same technology, known as T-cell receptor therapy. With the new products in the pipeline, the company aims to treat other forms of cancer, autoimmune diseases, and infectious diseases, such as hepatitis.

The company reports its fourth quarter on March 2 ahead of the market opening. Wall Street is eyeing a loss of $0.03 per share on revenue of $38.68 million. That would be a year-over-year revenue increase of 335%. 

In its most recent earnings report, the company said total net product and net pre-product revenue from the sale of Kimmtrack and tebentafusp, its chemical name, was $40.4 million in the three months ending September 30, 2022. The company also had $5.451 million in collaboration revenue from discovery partnerships with Genentech, Eli Lilly and Company (NYSE: LLY), and GSK PLC (NYSE: GSK) to develop new cancer therapies Immunocore’s technology platform. 

Its total revenue of $45,871 in the most recent quarter was a 476% year-over-year increase. That stands to reason, as Kimmtrak only received FDA approval in January 2022. Revenue ramped up in the quarter ending in March 2022 and grew at triple-digit rates in the past three quarters. 

The company swung to profitability in the most recent quarter, earning $0.13 per share. 

MarketBeat earnings data for Immucore show the company significantly topped earnings and sales views in the past three quarters. 

For the full year of 2022, Immunocore is expected to report a loss of $0.40 per share, narrowed from the 2021 loss of $4.13 per share. That loss is expected to remain at $0.40 a share this year. 

Immunocore has posted strong, market-beating gains in the past year. The stock is up 163.05% on a one-year basis. It’s up 16.01% in the past month and 12.06% in the past three months. 

Tracked By Nasdaq Biotech Index

The stock is not a component of any major indexes, but it’s part of the Nasdaq Biotechnology Index, as tracked by the Invesco Nasdaq Biotechnology ETF (NYSEARCA: IBBQ). It only comprises 0.15% of fund assets, but it never hurts to be part of an index. That means ETFs tracking the index have to buy enough of the stock’s shares to maintain balance.

The buyers are clearly in charge. According to MarketBeat institutional investor data for Immunocore, in the past 12 months, 43 institutional buyers accounted for inflows of $179.00 million. 19 institutional sellers accounted for outflows of $36.34 million during that time. 
Is Biotech Immunocore About To Make A 25% Price Move?

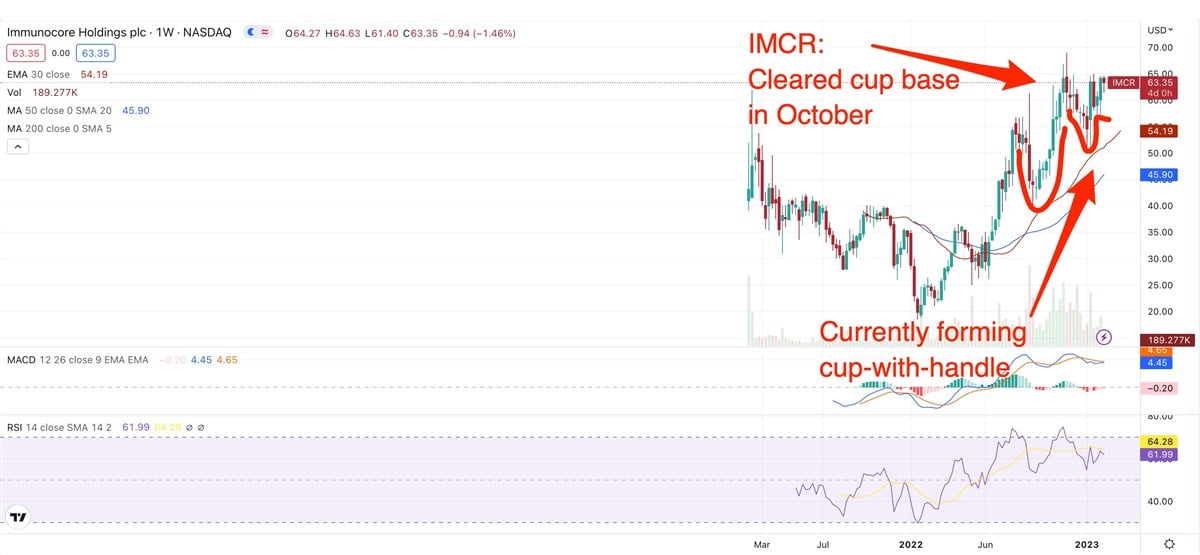
The stock broke out of a cup-shaped base with a buy point above $61.32 in late October, then rallied to a high of $69.06 on November 18 before retreating into a new consolidation. The current base is taking a cup-with-handle shape with a potential buy point just above $65. It’s hit resistance between $64 and $65 in the past three sessions. 

Although Immunocore is not yet profitable, the institutional ownership data and recent uptrends signal that the stock has the potential to rise further. Analysts have a price target of $79.13, representing an upside of 25.18%. Analysts have a “buy” rating on the stock.

Recent News