Stock of the Day

January 2, 2024

MongoDB (MDB)

$366.49
+$10.20 (+2.9%)
Market Cap: $28.70B

About MongoDB

MongoDB, Inc., together with its subsidiaries, provides general purpose database platform worldwide. The company provides MongoDB Atlas, a hosted multi-cloud database-as-a-service solution; MongoDB Enterprise Advanced, a commercial database server for enterprise customers to run in the cloud, on-premises, or in a hybrid environment; and Community Server, a free-to-download version of its database, which includes the functionality that developers need to get started with MongoDB. It offers professional services comprising consulting and training. The company was formerly known as 10gen, Inc. and changed its name to MongoDB, Inc. in August 2013. MongoDB, Inc. was incorporated in 2007 and is headquartered in New York, New York.

MongoDB Bull Case

Here are some ways that investors could benefit from investing in MongoDB, Inc.:

  • MongoDB, Inc. recently reported strong financial performance for the quarter ended September 1, 2026, with revenue of $771.77 million, which exceeded analyst expectations of $735.01 million and represented a 30.5% year-over-year increase, demonstrating robust demand for its database platform.
  • The company's earnings per share of $1.90 for the same period beat the consensus estimate of $1.62 by $0.28, indicating that MongoDB, Inc. is effectively converting its revenue growth into profitability, a key metric for investors assessing operational efficiency.
  • Wall Street analysts maintain a positive outlook on the stock, with a consensus rating of "Moderate Buy" and an average price target of $462.59, which suggests significant upside potential from the current stock price of $381.29 as of October 12, 2026.
  • Institutional investors are increasing their exposure to the company, as evidenced by Zevenbergen Capital Investments LLC increasing its stake by 26.8% in the third quarter and MassMutual Private Wealth & Trust FSB adding 8,000 shares, signaling confidence in the long-term trajectory of MongoDB, Inc.
  • The company has announced a major buyback expansion of $1.35 billion, a move that typically signals management's confidence in the company's future cash flows and its commitment to returning capital to shareholders, which can support stock price stability.

MongoDB Bear Case

Investors should be bearish about investing in MongoDB, Inc. for these reasons:

  • MongoDB, Inc. trades at a premium valuation with a P/E ratio of 537.03, which is significantly higher than typical market averages, meaning investors are paying a substantial amount for each dollar of earnings, a risk if growth slows or margins compress.
  • There is a pattern of insider selling, with Director Charles Hazard, Jr. selling 595 shares on October 6, 2026, and other directors like Dwight Merriman and Hope Cochran also selling shares in recent months, which can be interpreted as insiders taking advantage of high stock prices to reduce their personal exposure.
  • The stock has experienced high volatility, as indicated by a beta of 1.74, which means MongoDB, Inc. is more volatile than the overall market, potentially leading to larger price swings that may not align with the company's fundamental performance.
  • Short interest in the stock has been notable, with 2,831,157 shares shorted as of September 30, 2026, representing 3.61% of the float, suggesting that a portion of the market is betting against the stock's future performance, which can create downward pressure on the price.
  • Despite strong revenue growth, the company's net margin is relatively low at 2.12% for the most recent quarter, indicating that a significant portion of revenue is consumed by operating expenses, which could limit the company's ability to generate substantial free cash flow for reinvestment or shareholder returns.

Selling the news in MongoDB is a buy-the-dip opportunity

Written By Thomas Hughes on 12/6/2023

MongoDB stock price

MongoDB’s (NASDAQ: MDB) share price fell about 5% following the Q3 release in what can only be a sell-the-news event. The company produced high double-digit growth that beat the consensus estimates and raised guidance, which should have been a catalyst for higher share prices. The problem for MDB is that the analysts' consensus forecast failed to account for momentum in the AI industry and this business specifically. There were numerous hints that strength should be expected. 

Not only are the big players like Oracle (NYSE: ORCL), Microsoft (NASDAQ: MSFT) and Amazon’s (NASDAQ: AMZN) AWS benefiting from the shift to AI-powered clouds, but virtually every cloud-based business providing utility via AI is outperforming in this environment. So, the outperformance presented by MDB was generally expected but is still a significant force for the market and one that will elevate the stock price over time. And the positive guidance is probably very cautious. 

MongoDB has a blowout quarter, raises guidance 

MongoDB had a blowout quarter driven by forces felt by most AI-centric cloud companies today: customer growth and deepening penetration of services. The company reported a 1000 basis point slowdown in YOY growth compared to Q2, but the $432.94 million in revenue is up 30% and beats the Marketbeat.com consensus by 710 basis points. 

Customer count is up 17% YOY and bolstered by new business from existing. Subscriptions are up 30% YOY to 66% of revenue, with services trailing with a 13% gain. Strength was seen across all verticals, geographic regions and customer segments, proving a solid foundation for future growth. 

The margin is equally impressive and driven by substantial revenue leverage. The company’s gross margin improved by 300 basis points GAAP and adjusted to drive substantial strength on the bottom line. The GAAP results still show YOY losses, but the adjusted earnings and cash flow growth are robust. Adjusted earnings are up more than 3X YOY with positive free cash flow compared to last year’s loss. This solidifies the balance sheet, and the company is positioned for continued success. 

Guidance is good… and cautious

MongoDB’s guidance is excellent because it was raised above consensus and is most likely cautious. The company expects Q4 revenue from $429 to $433, suitable for 20% YOY growth, but a pause in sequential growth is unlikely. Earnings are expected to be in the range of $0.44 to $0.46 compared to the $0.36 estimate, robust enough but low compared to the Q2 and Q3 strength and a decline compared to last year. It is more likely that MDB will post a sequential uptick in revenue and wider-than-forecast margins that could be substantially better than expected. New tools like the Vector Search make it even easier for development teams to harness data and drive innovation. 

Analysts are on board the MDB freight train but have yet to issue major updates or revisions to their outlook or price targets. Until then, the trend in sentiment has been bullish, with numerous boosted price targets, reiterated bullish ratings, initiated coverage and even an upgrade since the last report. Investors should expect this trend to continue because the Q3 results were strong, and the guidance was above target. The caveat now is that the consensus target assumes fair value near the recent highs and may cap gains until (if) the analysts begin to up their targets. 

The technical outlook: MongoDB pulls back to buy zone

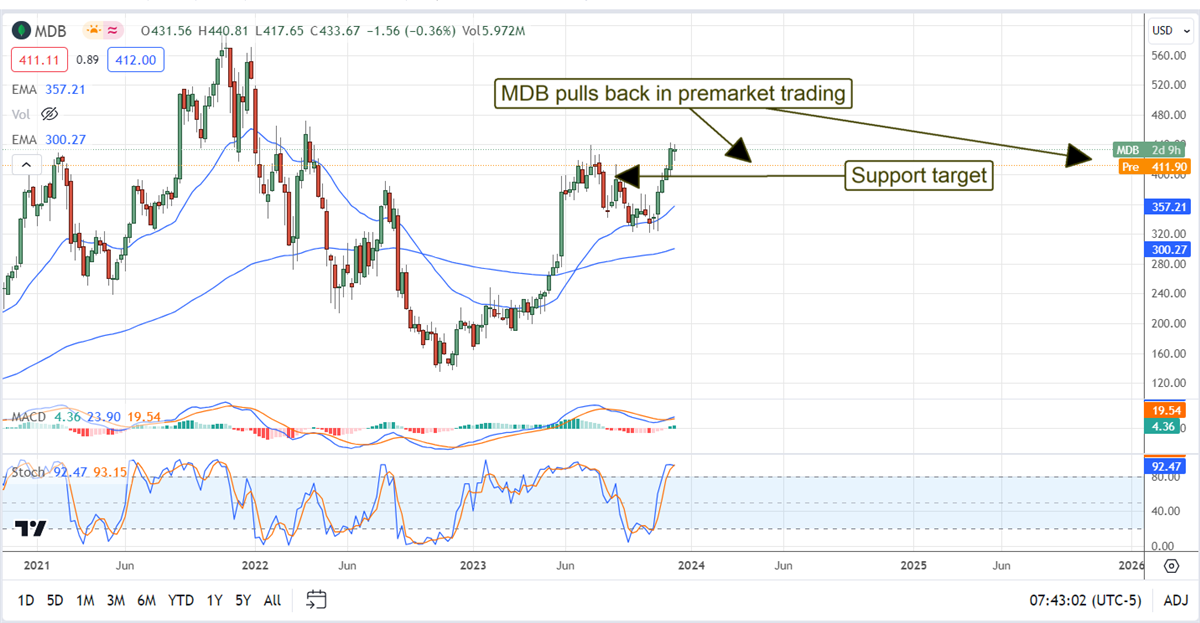
The price action in MDB pulled back about 5% following the earnings release but may already be at support. The market fell back to the summer congestion zone, where buyers will likely be found. Assuming the market steps in to buy the stock at this level, it should consolidate here and then continue upward to align with the trend. If not, MDB shares could pull back below $400 and offer an even better entry point. 
MongoDB stock price

Recent News