Stock of the Day

January 23, 2024

J.B. Hunt Transport Services (JBHT)

$235.31
+$3.15 (+1.4%)
Market Cap: $21.80B

About J.B. Hunt Transport Services

J.B. Hunt Transport Services, Inc. provides surface transportation, delivery, and logistic services in the United States. It operates through five segments: Intermodal (JBI), Dedicated Contract Services (DCS), Integrated Capacity Solutions (ICS), Final Mile Services (FMS), and Truckload (JBT). The JBI segment offers intermodal freight solutions. It operates 118,171 pieces of company-owned trailing equipment; owns and maintains its chassis fleet of 100,825 units; and manages a fleet of 5,944 company-owned tractors, 436 independent contractor trucks, and 7,567 company drivers. The DCS segment designs, develops, and executes supply chain solutions that support various transportation networks. As of December 31, 2023, it operated 12,574 company-owned trucks, 674 customer-owned trucks, and 4 contractor trucks. The company also operates 27,194 owned pieces of trailing equipment and 5,406 customer-owned trailers. The ICS segment provides freight brokerage and transportation logistics solutions; flatbed, refrigerated, expedited, and less-than-truckload, as well as dry-van and intermodal solutions; online multimodal marketplace; and logistics management for customers to outsource their transportation functions. The FMS segment offers delivery services through 1,166 company-owned trucks, 225 customer-owned trucks, and 20 independent contractor trucks; and 1,212 owned pieces of trailing equipment and 102 customer-owned trailers. The JBT segment provides dry-van freight services by utilizing tractors and trailers operating over roads and highways through 27 company-owned tractors and 13,561 company-owned trailers. It also transports or arranges for the transportation of freight, such as general merchandise, specialty consumer items, appliances, forest and paper products, food and beverages, building materials, soaps and cosmetics, automotive parts, agricultural products, electronics, and chemicals. The company was incorporated in 1961 and is headquartered in Lowell, Arkansas.

J.B. Hunt Transport Services Bull Case

Here are some ways that investors could benefit from investing in J.B. Hunt Transport Services, Inc.:

  • The stock is currently trading at $228.42, which is significantly below the consensus price target of $284.17, suggesting potential upside of over 24% if the market re-rates the company based on its recent strong performance.
  • Recent quarterly results demonstrated strong fundamental health, with the company beating analyst estimates for both earnings per share and revenue in the most recent report, showing a 19.4% year-over-year revenue increase and a net margin of 5.31%.
  • Wall Street maintains a "Moderate Buy" consensus rating, with 15 out of 26 analysts providing Buy or Strong Buy ratings, indicating broad institutional confidence in the company's long-term trajectory despite recent volatility.
  • The company offers a stable income stream for investors through its dividend, which has a yield of 0.81% and a conservative payout ratio of 25.50%, meaning the company retains the majority of its earnings for reinvestment while still rewarding shareholders.
  • Short interest has decreased to 2.22% of the float, a drop from higher levels earlier in the year, which often signals that short sellers are covering their positions and that market sentiment is shifting toward a more positive outlook.

J.B. Hunt Transport Services Bear Case

Investors should be bearish about investing in J.B. Hunt Transport Services, Inc. for these reasons:

  • Multiple law firms, including Rosen Law Firm and Pomerantz LLP, are actively investigating potential securities class action claims alleging that the company issued materially misleading business information, which introduces significant legal and reputational risk.
  • Recent analyst actions have been predominantly negative, with firms like Citigroup, JPMorgan, and TD Cowen lowering their price targets in the past few weeks, citing concerns that the freight recovery is largely supply-driven rather than demand-driven.
  • There is a notable divergence in analyst opinions, with Morgan Stanley maintaining an "underweight" rating and a price target of $200.00, which is below the current stock price, suggesting that some experts believe the stock is overvalued relative to its fundamentals.
  • Insider selling has been consistent, with multiple executives including the COO and several EVPs selling shares in the first half of 2026, which can be interpreted as a lack of confidence in the stock's near-term appreciation potential.
  • The stock has experienced significant volatility, trading down from a 52-week high of $299.76 to the current level, and Zacks research indicates the company lacks the specific estimate revision indicators typically associated with a likely earnings beat in the upcoming report.

J.B. Hunt stock at an inflection point with new highs in sight

Written By Thomas Hughes on 1/19/2024

J.B Hunt stock price

J.B. Hunt Transport Services (NASDAQ: JBHT) struggled in Q4, which will continue in the year's first half, but an inflection point is at hand. The timing of the inflection is uncertain, but volumes are rising in critical segments and are a leading indicator of pricing for the transportation sector. 

Volumes rose in the JBI or intermodal segment, supported by increased transcontinental shipments, related at least partly to issues with both significant canals. Traffic is diverting from the Suez Canal because of war and the risk of attack, while traffic in the Panama Canal is impacted by drought. Ship crossings are reported to be down 36% YOY at the Panama Canal because of low water and all that freight has to get across somehow. Drought conditions are not expected to improve soon, and war in the Middle East seems to be escalating. 

The takeaway is that J.B. Hunt is navigating the challenging environment well enough, and the outlook has greatly improved. The company doesn’t give specific guidance for revenue and earnings, but the expected increase in tax rate foreshadows improved profits, aligning with the analysts' forecasts. A consensus of twenty analysts forecasts top and bottom-line growth returns this fiscal year and accelerates into 2025, supporting the outlook for shareholder value and capital returns. 

J.B. Hunt struggles in Q4; to focus on operational quality in 2024

J.B. Hunt had a mixed quarter, with volume increases more than offset by yield pressure and rising costs. The company reported $3.3 billion in net revenue for a decline of 9.6% but outpaced consensus by $30 million. The primary area of weakness is in pricing. Realized pricing fell 10% to 15% across segments and was compounded by volume declines in some. JBI, the intermodal segment, is one of the areas of strength where volume increased by 7%, underpinned by a 13% increase in transcontinental. Assuming that volume remains solid, pricing should increase and improve the revenue and margin. 

The margin was an area of weakness in Q4 but was offset by hopes that a rebound would form. The company’s margin contracted more than expected due to yield pressures and rising costs that include higher insurance claims. The takeaway is that Q4 and FY cash flow remain solid, with the quarterly take positive despite an increase in CAPEX. CAPEX focuses on improving fleet size and quality, shifting consumers to intermodal and operational efficiency, which all play into the 2024 outlook.

J.B. Hunt will deliver for shareholders in 2024

As tepid as the Q4 results are, the company’s cash flow and balance sheet are sufficient to sustain the capital return outlook, including dividends and share repurchases. The company raised its dividend by 2% with the Q4 release aligning with expectations. The new payout annualizes to 0.85%, which is small but compounded by safety and repurchases. Regarding distribution safety, the company pays less than 25% of its earnings as dividends, has very low leverage, and has an unencumbered balance sheet with ample coverage.

Repurchases aren’t enormous but are sustainable at their current levels. Repurchases in Q4 amounted to $25 million or 0.12% of the market cap, leaving $392 million under the current authorization. The share count is down 0.5% YOY and should continue to decline over the next four quarters. 

J.B. Hunt on the road to new highs; analysts are in the driver's seat

J.B. Hunt shares are on track to reach new highs and are up more than 4% in premarket trading, but there is a hurdle. The market is trading in a way that is aligned with the analysts' consensus, which may provide a ceiling. The upshot is that sentiment has warmed over the last six months, and the 2024 revisions are positive. The high target was set in December but is in play with price action rising and the consensus price target edging higher ahead of the report. It suggests the market will move 10% above the current high. J.B. Hunt shares should be able to break resistance and set a new high if this trend continues.  
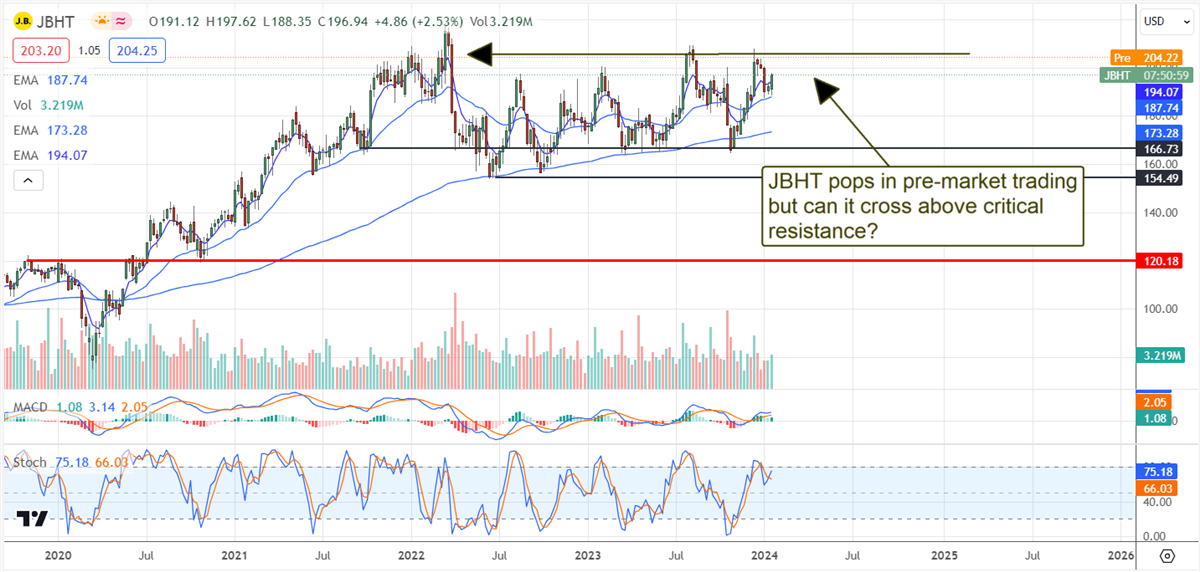
JB hunt stock chart

Recent News