Stock of the Day

May 29, 2023

Skyworks Solutions (SWKS)

$79.10
+$2.21 (+2.9%)
Market Cap: $11.57B

About Skyworks Solutions

Skyworks Solutions, Inc., together with its subsidiaries, designs, develops, manufactures, and markets proprietary semiconductor products in the United States, China, South Korea, Taiwan, Europe, the Middle East, Africa, and the rest of Asia-Pacific. Its product portfolio includes amplifiers, antenna tuners, attenuators, automotive tuners and digital radios, DC/DC converters, demodulators, detectors, diodes, wireless analog system on chip products, directional couplers, diversity receive modules, filters, front-end modules, hybrids, light emitting diode drivers, low noise amplifiers, mixers, modulators, optocouplers/optoisolators, phase locked loops, phase shifters, power dividers/combiners, power over ethernet, power isolators, receivers, switches, synthesizers, timing devices, voltage controlled oscillators/synthesizers, and voltage regulators. The company products are the used in aerospace, automotive, broadband, cellular infrastructure, connected home, defense, entertainment and gaming, industrial, medical, military, smartphone, tablet, and wearable markets. It sells its products through direct sales force, electronic component distributors, and independent sales representatives. Skyworks Solutions, Inc. was founded in 1962 and is based in Irvine, California.

Today's Trend

Skyworks Solutions, Inc. (NASDAQ: SWKS) is benefiting from a generally supportive news flow following its completed combination with Qorvo, although analysts remain divided over execution and handset-market risks.

  • Analyst upgrades and higher targets: B. Riley upgraded SWKS from Neutral to Buy and raised its price target to $107 from $68, implying substantial upside. Citigroup also lifted its target to $90, though it retained a Neutral rating. B. Riley upgrades Skyworks Solutions
  • Qorvo merger synergies: Coverage continues to highlight the combined company’s broader RF-chip portfolio and an expected $500 million in annual cost savings within three years. The potential for improved scale and margins is supporting the investment case. Skyworks completes Qorvo deal
  • New product milestone: Skyworks said its Si829x isolated safety gate driver has completed qualification and is ready for customer evaluation, providing a potential avenue for growth in industrial and automotive applications beyond smartphones. Skyworks Si829x product announcement
  • Lower short interest: Short interest declined 5.34% to 32.7 million shares, or 34.44% of the float. While still elevated, the reduction may ease bearish pressure and leaves potential for short covering if merger execution improves. Skyworks short interest falls
  • Debt restructuring completed: Skyworks completed exchange offers involving Qorvo’s senior notes and announced new senior notes, an effort to streamline financing after the acquisition. The move may improve debt management but also underscores the added leverage and financing complexity from the deal. Skyworks streamlines debt
  • Valuation and execution concerns: Fair-value estimates around $69.82 and a median analyst target of $75 remain below the recent trading level. Analysts are split on whether the Qorvo integration and projected synergies can offset weak handset demand, margin pressure and continued smartphone exposure. Skyworks fair value and Qorvo deal analysis

Skyworks Solutions: Another Crack in the Consumer Outlook

Written By Thomas Hughes on 5/9/2023

Skyworks Solutions Inc. image on MarketBeat

Skyworks Solutions Inc. (NASDAQ: SWKS) does not have a consumer-facing business. Still, it makes many of the gadgets and gizmos used by today’s top consumer-products companies, and the news in the Q2 report does not inspire confidence. News from Packaging Corporation of America and United Parcel Service points to a widespread slowdown in consumer discretionary spending. A larger-than-expected slowdown in volume should impact results, and higher prices will not offset the difference. 

In addition, the guidance from United Parcel Service Inc. (NYSE: UPS) and Packaging Corporation of America (NYSE: PKG) was less than hopeful and suggested that volumes will continue to decline — they will focus on operational quality. They, and many other corporations, cut back on spending and staffing in a way that will extend and possibly accelerate the declines in volume already being reported. 

What this means for Skyworks Solutions stock is a year-over-year (YOY) decline in revenue and profits, tepid results relative to the analysts' expectations and weak guidance. All sparked another round of price target reductions that will cap gains in 2023. The 25 analysts with current ratings have the stock pegged at a "moderate buy," but even that is slipping. There have been at least 12 new commentaries, including 12 price target reductions and one downgrade from "outperform" to "market perform." The sentiment may not shift much over the next few months, but the price target is down compared to last year and last month and may be expected to fall further as economic data becomes available. 

Skyworks Falls on Tepid Results

Given the conditions, Skyworks didn’t have a terrible quarter, but the news suggests the downturn is ongoing. Its revenue of $1.15 billion is down 14.2% compared to last year, and the guidance calls for the same in Q3. The range allows for some strength, but the high end is below the consensus target, and it may be an optimistic outlook. 

The company was able to sustain margin compared to last year but even that news is mixed. The gross margin contracted by 200 basis points on rising costs but internal efficiencies, including reduced spending and SG&A expense, offset the decline. This left adjusted earnings at $2.02, down more than 25 cents compared to last year and short of consensus by a penny which is not rally-inducing. 

The factor that may keep the stock from falling significantly lower is the dividend. Revenue and earnings are in decline, but cash flow remains robust and sufficient to cover the distribution. The company paid out 62 cents per share for the quarter of $2.48 annualized, or about 30% of the newly reduced earnings outlook. 

Institutional Interest to Help Support the Action 

The institutions have been buying Skyworks for three consecutive quarters and helped to put a bottom in the stock. Assuming this continues, Skyworks shares can be expected to continue within the current trading range. The second quarter guidance has the market moving lower, so a test of support at $85 is possible, although the $100 level appears to be firm support now. Longer-term, this stock should recover nicely because it is a major supplier to Apple, and Apple will continue to dominate the consumer tech market. 
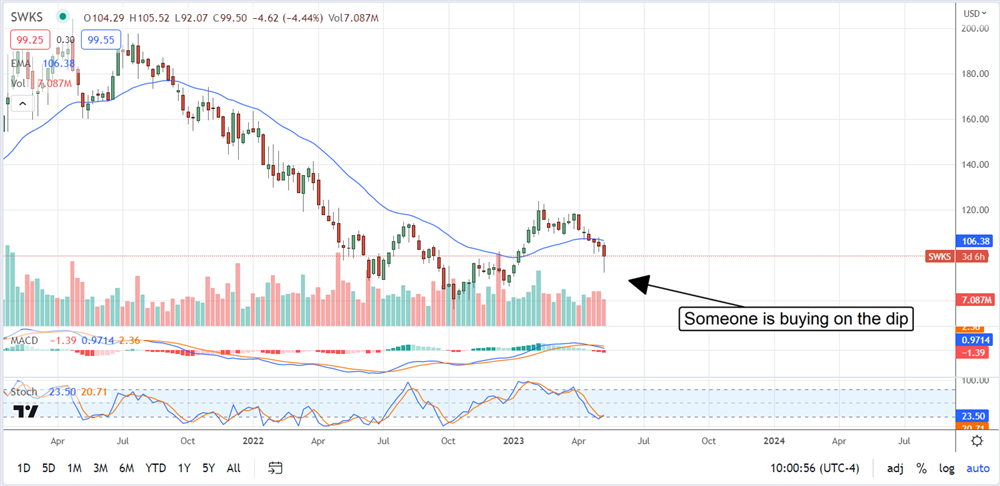
Chart of Skyworks on MarketBeat

Recent News